Skilled Nursing Occupancy Flat in July 2022

NIC MAP Vision released its latest Skilled Nursing Monthly Report on September 29, 2022. The report includes key monthly data points through July 2022.

“In addition to managing occupancy and staffing challenges, skilled nursing operators need to be laser-focused on reimbursement at the state level as Medicaid represents 51% of revenue.”

– Bill Kauffman          

NIC MAP Vision released its latest Skilled Nursing Monthly Report on September 29, 2022. The report includes key monthly data points from January 2012 through July 2022.

Here are some key takeaways from the report:

Skilled nursing property occupancy was relatively flat in July. It ended the month at 78.1%. In the last five months, skilled nursing occupancy has hovered in the range of 78% which is the highest occupancy level since April 2020, at which time occupancy began to fall rapidly due to the onset of the pandemic. Occupancy continues to recover since the pandemic low of 72.9% set in January 2021 but has encountered challenges such as new COVID-19 variants and staffing shortages. Staffing shortages continue to create difficulties within skilled nursing properties limiting the ability to admit new residents in some markets. However, the current occupancy trend does suggest that demand for skilled nursing properties is recovering, given the 148-basis point increase from January to July this year (2022). Occupancy has increased 151 basis points from one year ago and 517 basis points from its pandemic low.
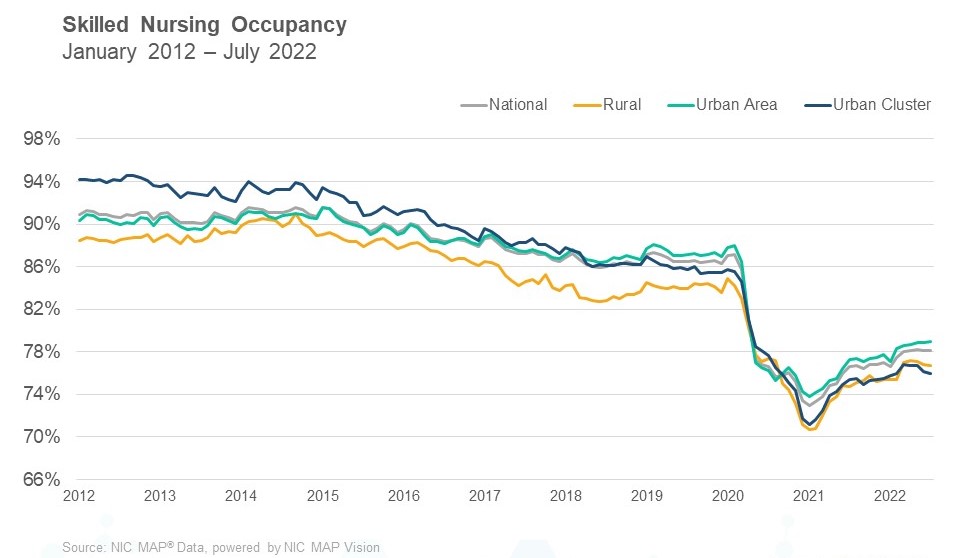
SNF Occupancy July 2022

Managed Medicare revenue per patient day (RPPD) continued its decrease in July. It decreased from $460 to $458 in July and is down 1.1% from last year in July 2021. It has decreased $112 (19.6%) from January 2012. The persistent decline in managed Medicare revenue per patient day continued to result in an expanded reimbursement differential between Medicare fee-for-service and managed Medicare, which accelerated during the pandemic until January 2022. The difference between Medicare fee-for-service and managed Medicare RPPD in January 2022 was $127. Pre-pandemic, in February of 2020, the differential was $95. However, the difference has decreased since January 2022 to end July 2022 at $115. Meanwhile, managed Medicare revenue mix was flat from June to July at 10.5%. It is up, however, 21 basis points from last year and has increased 244 basis points from the pandemic low of 8.1%. The increase from the pandemic low is likely due to growth in surgeries that require rehab, which typically creates additional referrals to skilled nursing properties.

Medicare revenue mix declined 25 basis points to end July at 21.9%. After increasing to start 2022, from December 2021 (20.7%) to January 2022 (24.8%), it has now decreased 308 basis points from the 2022 high (25.0%) set in February. The increase at the start of 2022 was likely due to the elevated number of COVID-19 cases in January and suggests there was a significant uptick in the utilization of the 3-Day Rule waiver as COVID-19 cases increased. The 3-Day Rule waiver was implemented by Centers for Medicare and Medicaid Services (CMS) to eliminate the need to transfer positive COVID-19 patients back to the hospital to qualify for a Medicare paid skilled nursing stay, hence increasing the Medicare census at properties. As cases declined, the Medicare revenue share has declined as well. Meanwhile, Medicare revenue per patient day (RPPD) decreased to the lowest level of 2022 to end July at $574, which is down 2.6% from January. One possible explanation is there has been lower reimbursement due to relatively fewer COVID-19 cases compared to January 2022. Additional reimbursement is needed for COVID-19 positive residents, which requires additional measures of care to be implemented.  

Medicaid revenue mix increased 99 basis points from June to end July at 51.0%. It has increased 307 basis points since February. Some of this increase is related to what was mentioned above, regarding the decline in COVID-19 cases since the winter months and patients have now moved from Medicare patient days back to Medicaid, after utilizing the 3-Day Rule waiver. Meanwhile, Medicaid revenue per patient day (RPPD) increased from June to end July 2022 at $258. It is up 4.9% from the pre-pandemic period (February 2020) as many states embraced measures to increase reimbursement related to the number of COVID-19 cases to support skilled nursing properties, in addition to fiscal year increases.
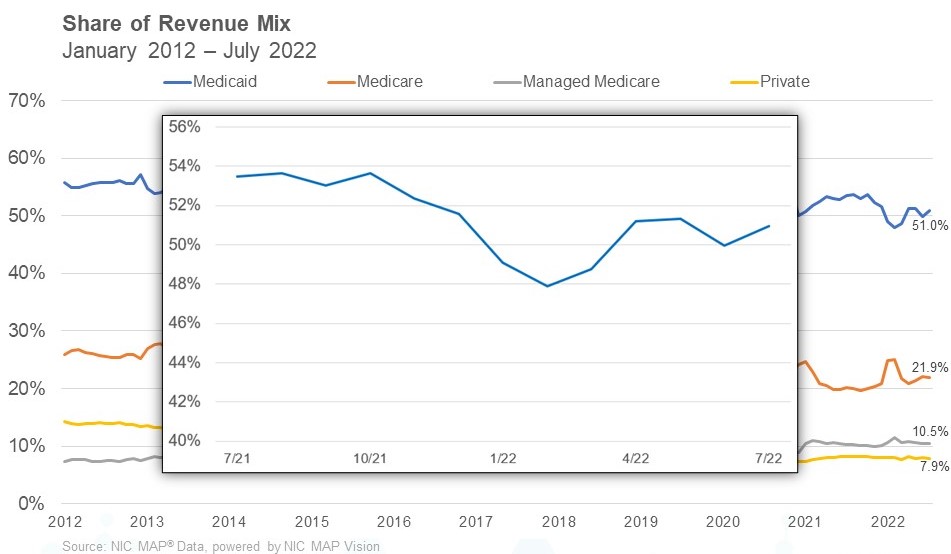
SNF Revenue Mix

To get more trends from the latest data you can download the Skilled Nursing Monthly Report. There is no charge for this report.

The report provides aggregate data at the national level from a sampling of skilled nursing operators with multiple properties in the United States. NIC continues to grow its database of participating operators to provide data at localized levels in the future. Operators who are interested in participating can complete this participation form. NIC maintains strict confidentiality of all data it receives.
Executive Survey Insights Wave 45: August 22 to September 18, 2022

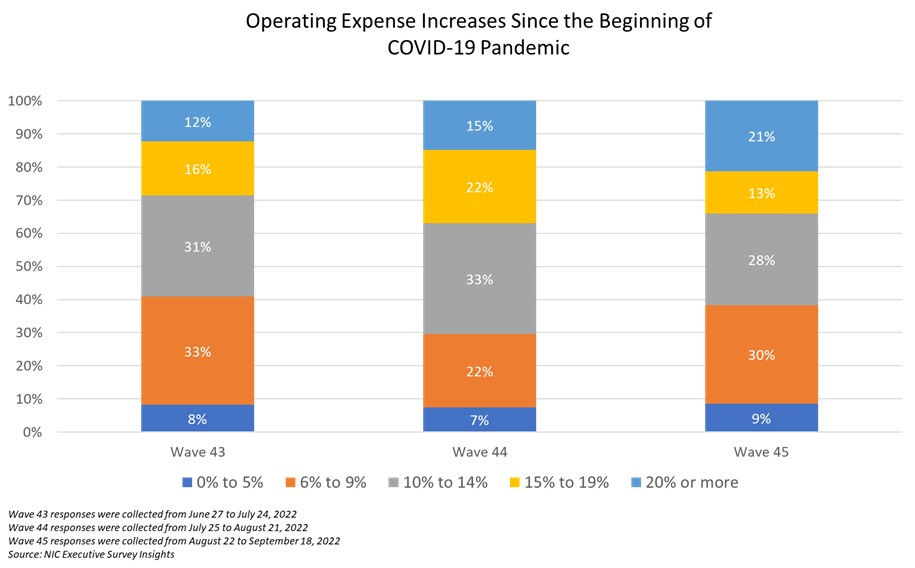
ESI Wave 45 shows operating expenses continue to rise with 21% of respondents reporting operating expenses 20% or more greater than prior to the pandemic.

“Just under one-fifth of respondents noted that the severity of staffing shortages across their organization was severe, while two-thirds indicated the problem was moderate. Regarding tenure of newly hired, full-time employees, on average, just under one-third (29%) of organizations kept more than 80% of new staff on the job after one month, which is down from the Wave 39 survey, conducted in March 2022, when just under one-half (46%) of respondents kept more than 80% on the job after one month.

Staffing retention difficulties often lead to increased agency usage, and in turn, both often have a detrimental impact on operating expenses and NOI. Operating expenses continue to rise, with more than one-fifth (21%) of respondents reporting operating expenses that are 20% or more greater than prior to the pandemic. Among the reasons given for the increase in operating expenses are vendor pricing, food costs, overtime and third-party agency usage, utilities, and insurance. Additionally, multiple respondents explicitly underscore industry-specific compensation increases that are above the rate of inflation.”

–Ryan Brooks, Senior Principal, NIC

This Wave 45 survey includes responses from August 22 to September 18, 2022, from owners and executives of 47 small, medium, and large senior housing and skilled nursing operators across the nation, representing hundreds of buildings and thousands of units across respondents’ portfolios of properties. More detailed reports for each “wave” of the survey and a PDF of the report charts can be found on the NIC COVID-19 Resource Center webpage under Executive Survey Insights.

ESI Wave 45 Move In Pace

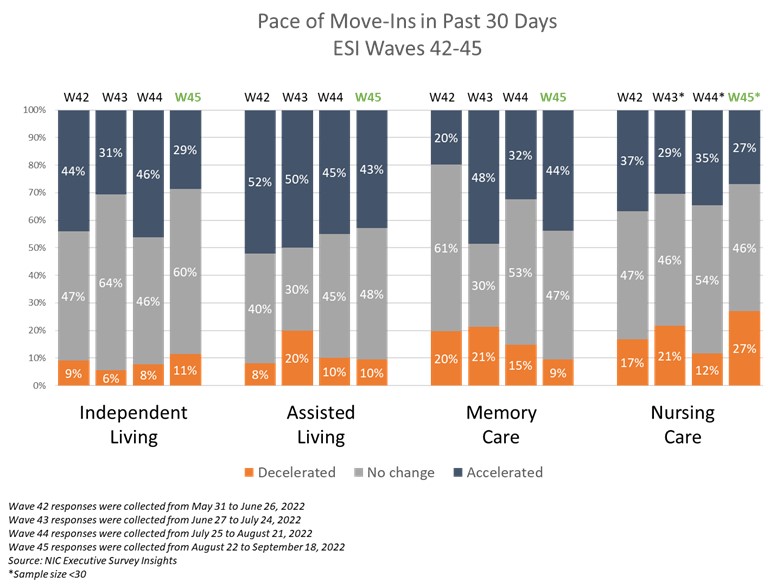
In the Wave 45 survey, reflecting operator experiences in August and September 2022, the rate of operators reporting an increase in the pace of move-ins in the past 30 days fell for independent living properties (29%), assisted living properties (43%), and nursing care properties (27%), but went up for memory care properties (44%). This marks the third consecutive wave with a decline in assisted living properties reporting an increase in the pace of move-ins.

Just under one-fifth of Wave 45 respondents indicated the severity of their staffing shortages across their organizations was severe (19%), while two-thirds (67%) reported it was moderate. Over 20% of respondents report staffing shortages across the entirety of their portfolio. Approximately one-quarter report staffing shortages at up to 25% of their properties, one-third have staffing shortages at up to 50% of their properties, and one-quarter report shortages at between 50%-99% of their properties.

ESI Wave 45


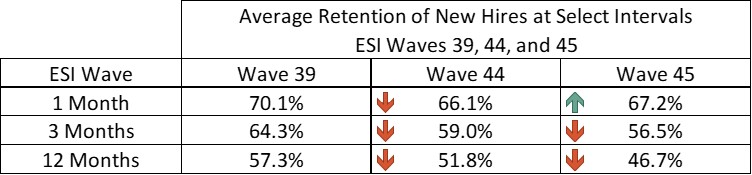
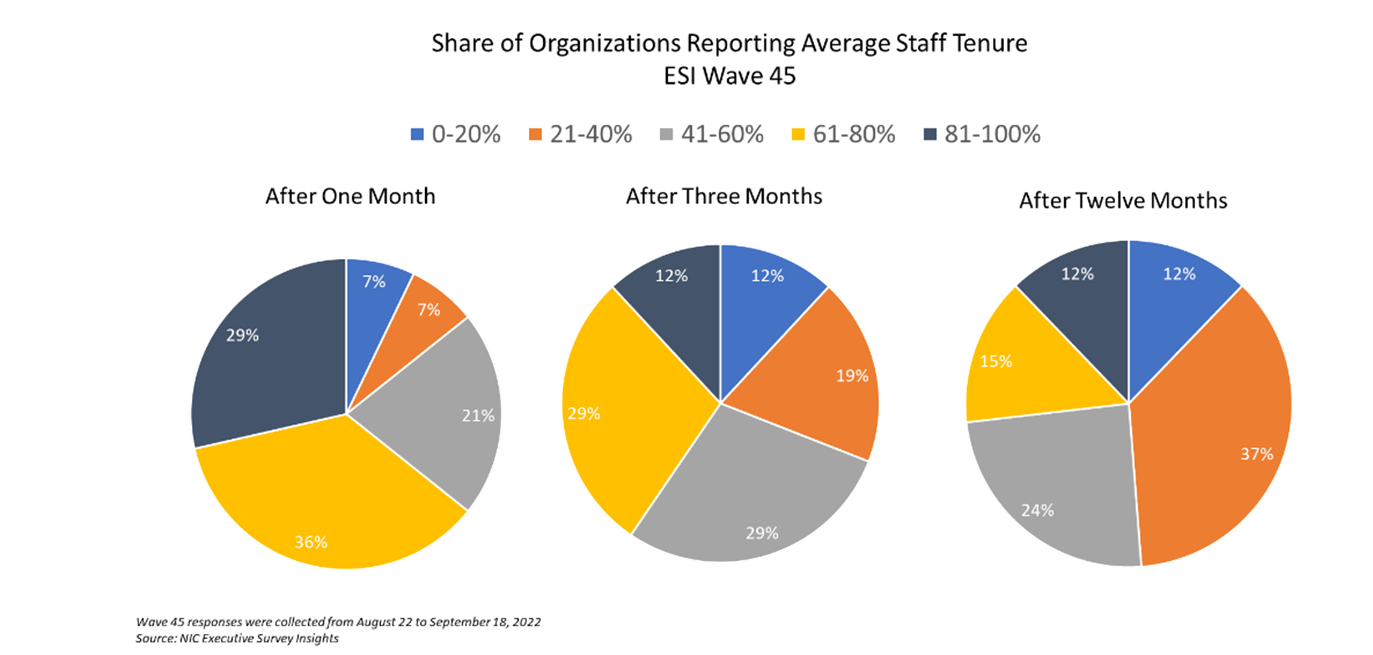
Regarding tenure of newly hired, full-time employees, on average, just under one-third (29%) of organizations kept more than 80% of new staff on the job after one month. This is down from the Wave 39 survey, conducted in March 2022, when just under one-half (46%) of organizations kept more than 80% on the job after one month. Looking at longer-term retention, on average, just over one-tenth (12%) of organizations retained more than 80% of new staff after one year. This metric is also down from the Wave 39 survey, conducted in March 2022, when just under one-sixth (16%) of organizations retained more than 80% of new staff at the one-year mark.

As indicated in the table below, the average share of newly hired employees that remain on staff after three months and after one year has decreased over each of the last three ESI surveys that included this question (Waves 39, 44, and 45). While the average share of newly hired employees that remain on staff after one month has remained relatively stable, long-term employee retention has become even more challenging.

ESI Wave 45 New Hire Retention


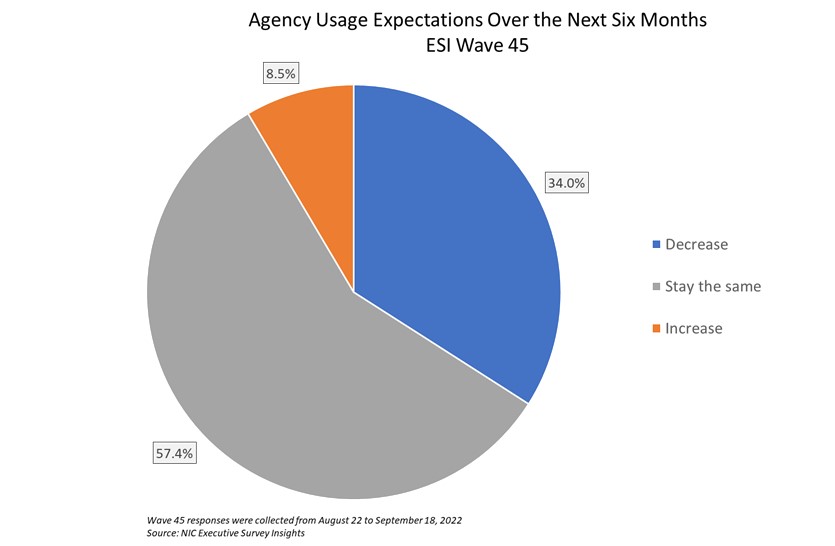
With employee retention remaining a challenge to operations, agency labor utilization is often turned to as a stopgap measure. When asked about their organizations’ expectations of agency usage in the next six months, 8.5% of Wave 45 respondents anticipate an increased reliance on agency staff, while two-thirds of respondents anticipate reliance on agency staff to decrease. Most respondents – 57% – anticipate their organizations’ agency usage to remain the same as it is currently.

ESI Wave 45 Agency Usage


Staffing retention challenges and a heavy reliance on agency usage can have a substantial impact on operating expenses and in turn NOI. When asked about the change in operating expenses since the beginning of 2022, 87% reported operating expenses to be higher and 13% reported operating expenses to have remained the same. No respondents had reduced operating expenses since the beginning of this year. When asked about the change in operating expenses since before the pandemic started, one-fifth of respondents have seen operating expenses increase by 20% or more.

ESI Wave 45 Operating Expenses

Reasons given for the increase in operating expenses include vendor pricing, food costs, overtime and third-party agency usage, utilities, and insurance. Multiple respondents explicitly underscore industry-specific compensation increases that are above the rate of inflation. One respondent indicated that frontline staff at their organization received an average increase of 24% in compensation. 

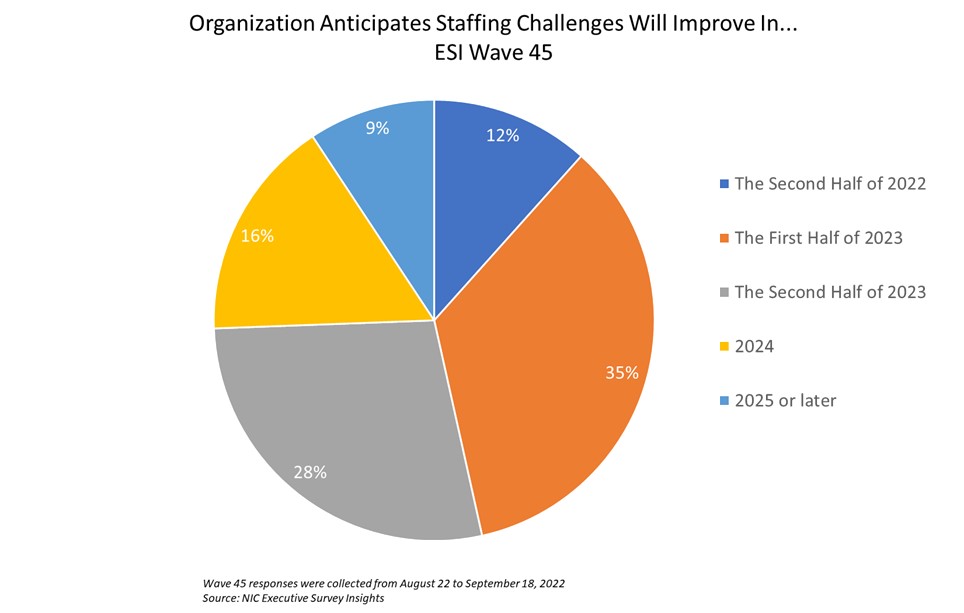
However, a promising sign of relief to the long-standing labor market issues may be that 12% expect staffing challenges to improve in the second half of this year. One-third believe labor markets will ease in the first half of 2023, approximately one-third believe staffing challenges will improve in the second half of 2023, and one in four anticipate it will take until 2024 or beyond before staffing challenges ease.

ESI Wave 45 Staffing Challenges


Wave 45 Survey Demographics

  • Responses were collected between August 22 and September 18, 2022, from owners and executives of 47 senior housing and skilled nursing operators across the nation. Owners/operators with 1 to 10 properties comprise roughly two-thirds (66%) of the sample. Operators with 11 to 25 properties account for 21%, and operators with 26 properties or more make up the rest of the sample with 13%.
  • One-half of respondents are exclusively for-profit providers (49%), just under one-half operate not-for-profit seniors housing and care properties (45%), and 6% operate both.
  • Many respondents in the sample report operating combinations of property types. Across their entire portfolios of properties, 66% of the organizations operate seniors housing properties (IL, AL, MC), 21% operate nursing care properties, and 45% operate CCRCs – also known as life plan communities.

This is your survey! Owners and C-suite executives of seniors housing and care properties, please help us tell an accurate story about our industry’s performance. The ESI 2022 questionnaire has been shortened from prior surveys. While some standard questions will remain for tracking purposes, in each new survey wave, new questions can be added based on respondents’ suggestions.

Wave 46 of the ESI is now live. The current survey is available and takes ten minutes to complete. If you are an owner or C-suite executive of senior housing and care and have not received an email invitation to take the survey, please contact Ryan Brooks at rbrooks@nic.org to be added to the list of recipients.

NIC wishes to thank survey respondents for their valuable input and continuing support for this effort to provide the broader market with a sense of the evolving landscape as we recover from the pandemic.

Women’s Networking Meetup: 15 Life Lessons for Professional Women in Senior Living

A Women’s Networking Meetup was held at the 2022 NIC Fall Conference in Washington, D.C. and Beth Mace shared career advice and life lessons.

An inaugural Women’s Networking Meetup was held last week at the 2022 NIC Fall Conference in Washington, D.C., co-sponsored by ASHA, Argentum’s Women in Leadership, the Senior Housing Women’s Initiative, and NIC. The gathering was designed to support women who remain underrepresented in senior living and allow them to get to know and support each other.

Beth Mace-2-2

Beth Mace, NIC’s Chief Economist, welcomed meetup attendees and shared some guiding principles and career advice from her own life. Mace’s remarks are shared below. 

“For those of you who don’t know me, my name is Beth Burnham Mace and I am the Chief Economist for NIC and have been in this role for the past eight years. I have been a practicing economist for my entire career in a range of industries from an electric utility to a bank to a think tank to a private equity group to working on Capitol Hill. About 25 years ago, while at AEW Capital Management, I became involved in senior housing and it totally hooked me and have been thrilled ever since to be involved in an industry that cares passionately for older adults.

IMG_4350

I am a mother of two sons, and have been married for many, many years. Like most of us, I have also faced a number of challenges along the way as well as a number of incredible opportunities and experiences. Being a woman and being the industry’s first chief economist is among them.

I have also been able to witness first-hand the changing role of women in society and professionally and I can say that while we have a lot of room to go forward, we’ve also come a long way baby as the phrase goes. For example, when I adopted my two sons, no maternity leave was offered since I was not physically pregnant. Today, many business offices provide lactation rooms. IMG_4342

As professionals, we wear many hats. Some of us are mothers, grandmothers, stepmothers, godmothers, wives, singles, widows, aunts, sisters, and cousins. Collectively, we support each other from a distance and from close proximity. Today, we hope to nurture more of those relationships as we support one another.

In preparation for today’s gathering, I thought I might provide you with some of the lessons I have learned along the way of life, with the hope that one of these observations may provide you with some insight, encouragement, or a bit of wisdom.

  1. HEALTH: It’s true what they say: if you have your health, you have everything. Indeed, as a multiple-time cancer survivor, I know personally that health is precious—mind your health.
  2. BALANCE: Balance is key, prioritization is key, saying no to certain things is okay, even good to do! You can’t do it all well, we need to compromise on some matters; know what’s important to you and make that your priority; and carry no guilt (easier said than done) regarding your family, work, or friends.
  3. LIFE IS NOT A DRESS REHEARSAL: Be the best version of yourself; life is not a dress rehearsal; find out what motivates you; do not let fear get in the way of anything.
  4. FLEXIBILITY: Be prepared for the shock waves that life sends to you; despite the best laid plans, life may have an alternative view; be flexible and roll with the punches.
  5. BE OPEN TO CHANGE: Be open to opportunity, challenge, and change.
  6. ATTITUDE: Attitude and narrative matter! You tell your story to the world, make it count and make it be the narrative you want. Look at the world as half full, not half empty: be an optimist.
  7. SELF CONFIDENCE: Have confidence in the choices you make and know that you are making the best decision you can at that moment in time with the information that you had at that moment.
  8. CARRY NO CHIPS ON YOUR SHOULDER: Try not to have regrets; learn to let go of things; don’t hang on to past angers and grudges; don’t have a chip on your shoulder (as my mother always said) or hold a grudge.
  9. PASSION: Find a job/career that energizes you and doesn’t deplete you; follow your passion if you are able.
  10. FOCUS: Make your professional hours professional; use them wisely and efficiently; stay focused; don’t hang around at the proverbial water cooler.
  11. LEARN: Be a student of life; keep educating yourself, engage with stimulating persons and put yourself in stimulating situations.
  12. IT TAKES A VILLAGE: It takes a village, no woman gets there alone. ASK for help and HELP each other personally and professionally. We pave the path for our daughters and next generation of women; help them, don’t add new obstacles for them (or make it tough on them because it was tough on you). Be around friends and family members that support and nurture you; surround yourself with positive role models and mentors, elders, and friends. Reach out to someone to be your mentor/coach.
  13. SELF-CARE/DESTRESS: Learn how to destress. Don’t burn out: take time for yourself, engage in self-care in whatever way you need or define it—diet, exercise, journaling, prayer, social activities, clubs, parenting activities, meditation, spirituality, dancing, laughing; find something that fulfills your heart, soul and essence.
  14. BEAUTY: Find beauty in your life because it will renew your spirit.
  15. FUN: Have fun! Laugh, engage, and party!

2022 NIC Fall Conference

I hope you find this meetup beneficial and I hope that you seed a few new female relationships. I, for one, know the benefits of women friends and know that there is nothing better.

As the years go by, I hope the seeds of these relationships will blossom into life-time connections with other women in our profession who carry the same torch you hold for caring for our seniors and older adults. And remember, let’s support each other today and as we move forward!”

Understanding the Healthcare Needs and Spending of Senior Housing and Nursing Home Residents

Understanding the Healthcare Needs and Spending of Senior Housing and Nursing Home Residents. NORC at the University of Chicago on behalf of NIC conducted a landmark study.

Understanding the healthcare needs of residents of senior housing communities and nursing homes is imperative to best serve the population. In order to garner a better understanding of these healthcare needs and associated spending, NORC at the University of Chicago on behalf of NIC conducted a landmark study. Many residents use high-cost healthcare services including emergency rooms, acute inpatient hospitalization, and post-acute care, and across nearly every dimension analyzed, the data indicates frail and high healthcare cost residents. These factors all highlight an opportunity for value-based care organizations to partner with senior housing and skilled nursing operators.

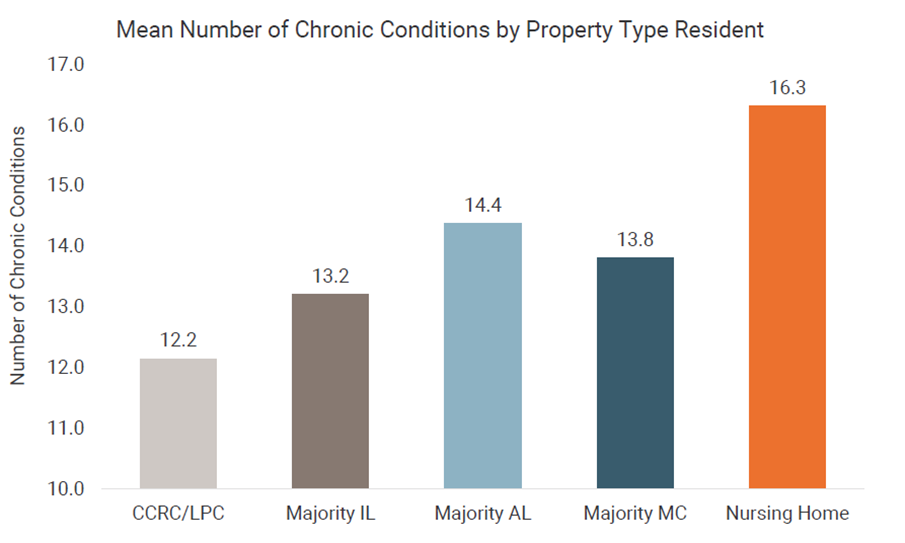
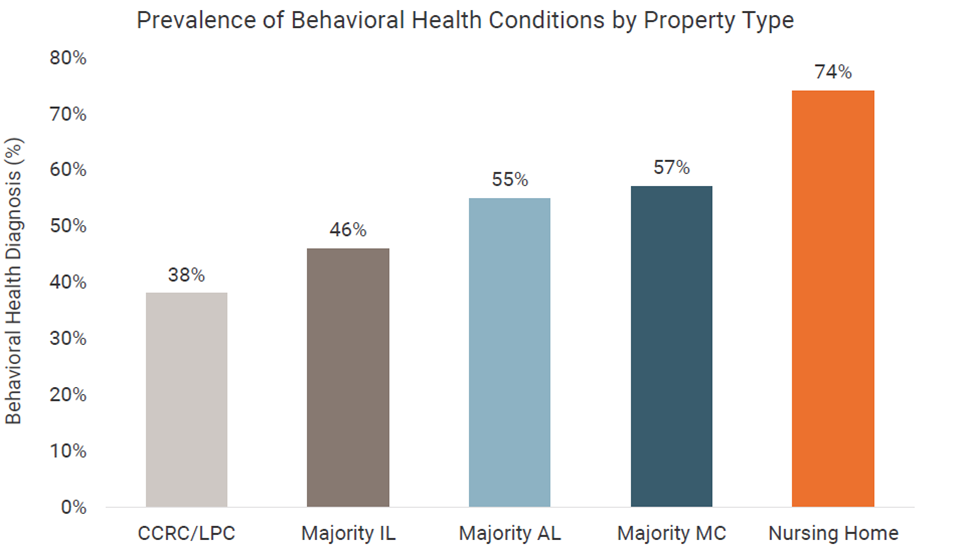
The study cohort of Medicare fee-for-service beneficiaries includes more than 250,000 senior housing residents and more than 325,000 nursing home residents. The study’s findings indicate that residents of senior housing and nursing homes average over a dozen chronic conditions and that behavioral health conditions are common.

norc-1-1norc-2-1

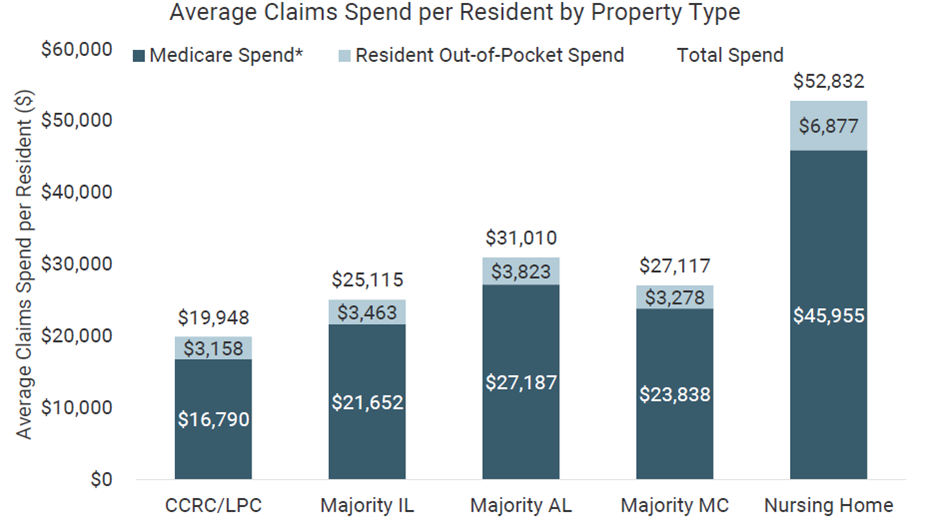
Senior housing residents have annual healthcare spending between ~$20,000 and $30,000, with between $3,000 and $4,000 out-of-pocket resident spending. Inpatient hospital and other institutional spending account for between 62% and 76% of a resident’s healthcare spend. By comparison, the average U.S. Medicare beneficiary incurs about $16,000 in annual healthcare costs. As such, reducing avoidable high-cost services is often a key focus of Medicare Advantage (MA) plans and other risk-bearing organizations.

norc-3-1

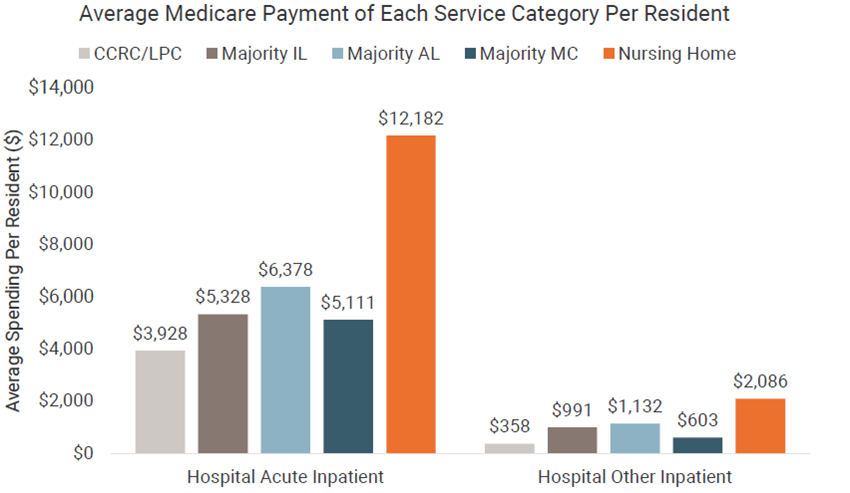
Spending on inpatient hospital care, including long-term care and rehabilitation, also suggests an opportunity for operators to build programs aimed at reducing hospitalizations.

norc-4-1

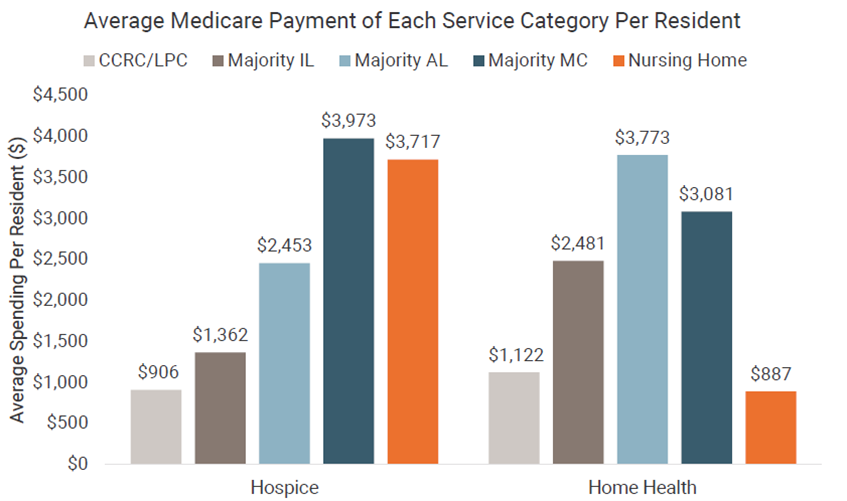
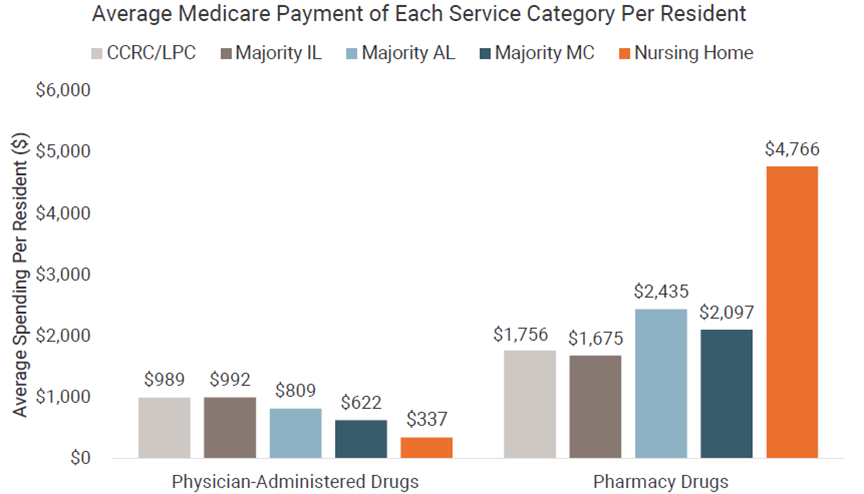
Additionally, senior housing residents have considerable hospice and home health spending. Home health services are predominantly for restorative therapy but may also involve skilled nursing and medication management. Medicare spending for both physician-administered and self-administered drugs also presents an opportunity to focus on medication therapy management and polypharmacy.

norc-5-1

norc-6-1

The methodology for the study utilizes an academically-designed data linkage approach which links property information from the NIC MAP® Data Service, powered by NIC MAP Vision, with Medicare Current Beneficiary Survey (MCBS) data and comprehensive administrative and claims data. With few data sources available to analyze the health needs of senior housing residents, this nationally representative survey allows senior housing and care stakeholders to better understand the health conditions that are most prevalent among their residents. With this understanding, proactive healthcare delivery strategies can be designed for the residents of senior housing communities and nursing homes.

To view the complete slide deck of findings, including methodology, inclusion criteria, age distribution, and service usage, download the slides here.


State of Senior Housing: The Trifecta Shaping the Occupancy Recovery

Senior housing occupancy still has room to make up with a gap of 5.8pps from the pre-pandemic level (87.2%) and has grown over the past four quarters.

During four consecutive quarters of increasing occupancy, from 78.0% in the second quarter of 2021 to 81.4% in the second quarter of 2022, the NIC MAP® Primary Markets recovered about 37% of the senior housing occupancy lost during the pandemic, equivalent to 3.4 percentage points (pps) overall.

While senior housing occupancy still has room to make up with a gap of 5.8pps from the pre-pandemic level (87.2%), occupancy growth over the past four quarters has been notable and suggests that the market’s recovery remains well anchored in the short and long term. In fact, according to August 2022 intra-quarterly NIC MAP data, powered by NIC MAP Vision, senior housing occupancy is on track for the fifth quarter of gain as it recorded its largest monthly gain in July 2022 since October 2021 and continued to improve through the month of August 2022.

Many factors continue to influence occupancy recovery for senior housing. This analysis will focus on a trifecta of factors – demand recovery (as measured by the change in occupied stock), inventory growth during the pandemic, and the construction pipeline (as measured by second quarter 2022 construction as percent of inventory) — and how these idiosyncratic factors are shaping the senior housing occupancy growth and recovery across NIC MAP Primary Markets, resulting in a slower recovery in some markets and faster in others. The exhibit below provides a zoomed-in view of these measures for senior housing across select NIC MAP Primary Markets since the pandemic began to influence the sector in first quarter 2020. 

Demand Recovery. Within the NIC MAP Primary Markets, 78% of senior housing units vacated during the pandemic have been re-occupied as of the second quarter of 2022, equivalent to over 35,500 units absorbed on a net basis over the period from first quarter 2021 to second quarter 2022. However, 28% of units lost during the pandemic (equivalent to about 10,000 units) still need to be reabsorbed for occupied stock to fully recover and return to first quarter 2020 level. Said differently, second quarter 2022 occupied stock remained 1.8% below first quarter 2020 level.  

Inventory Growth. Over the period from first quarter 2020 to second quarter 2022, the inventory of senior housing properties for the Primary Markets grew by about 34,700 units or 5.3%, although the pace of senior housing inventory growth since first quarter 2020 has remained slow compared with pre-pandemic levels.  

Construction Pipeline. Within the Primary Markets, there were over 35,000 senior housing units under construction in the second quarter of 2022. As a share of inventory, this amounted to 5.1%. Supply dynamics, including inventory growth during the pandemic and units under construction as a share of inventory, varied across markets.  

Senior housing occupancy up from pandemic low in all Primary Markets, but the occupancy recovery is taking a lot longer for some markets than others and has been influenced by both supply and demand dynamics. 

The Lowest Occupancy Rates in Second Quarter 2022. Atlanta and Cleveland experienced the fastest recoveries in terms of units vacated during the pandemic that have been re-occupied. Notably, these two markets saw the largest demand improvements and exceeded pre-pandemic first quarter 2020 occupied stock by 5.2% and 2.3%, respectively. However, due to their respective relatively large increases in inventory during the pandemic, Atlanta (77.8%) and Cleveland (78.2%) occupancy rates remained below pre-pandemic levels and ranked the lowest among the 31 Primary Markets. These two markets illustrate the impact of supply offsetting demand and putting downward pressure on a market’s average occupancy and thereby slowing down its recovery. 

Markets Near Full Occupancy Recovery. San Antonio (81.8%) and Dallas (82.4%) occupancy rates have been recovering fast. From their pandemic lows, San Antonio recovered 5.9pps and is now 1.5pps below its pre-pandemic level, and Dallas recovered 6.1pps and is now 1.4pps below its pre-pandemic level. Interestingly, the occupancy rankings for both markets among the 31 Primary Markets saw notable improvements—San Antonio went from being ranked twenty-eighth in first quarter 2020 to fourteenth in second quarter 2022, and Dallas improved from twenty-fourth in first quarter 2020 to tenth in second quarter 2022. These notable improvements in occupancy rates and rankings are the result of a fast recovery in occupied stock but also importantly a balanced new supply. 

Markets with the Highest Rates of Construction. Looking ahead, markets with the largest number of units under construction as a share of existing inventory, such as Miami, may experience a slowdown in occupancy growth as new units enter the market. This is also the case for Portland where demand recovery has been slow but due to relatively weaker inventory growth during the pandemic, the market maintained a relatively high occupancy rate in the second quarter of 2022 at 85.0%. However, second quarter 2022 units under construction of about 2,100 units and accounting for 9.8% of existing inventory may impact the market’s occupancy growth in the next two years if its pace of demand remains slow. 

This analysis showed that the senior housing industry has been on a steady recovery path from the pandemic since the middle of 2021, and the second quarter of 2022 was no exception. Recovery, while consistent nationally, has nevertheless varied by metro.

2022 NIC Notes Blog Occupancy 2Q2022

To learn more about NIC MAP Vision data, and about accessing the analysis for all NIC MAP Primary Markets, schedule a meeting with a product expert today.