The Conference That Changed My Career: Reflections on the NIC Scholar Program 


By Kate Abate, AdvoKate Longevity: Intergenerational Community Architecture 

The NIC Conference Scholar Program, sponsored by Welltower, gives students in senior housing academic programs full access to NIC’s Fall and Spring Conferences. Faculty at colleges and universities nominate students for the program.  

Selected Scholars take part in conference educational sessions and networking events. The program gives them a direct look at the issues shaping senior housing, and the chance to connect with industry leaders. Those connections often carry beyond the conference. Past scholars have gone on to internships and job offers in the field, and they stay involved with NIC as their careers develop. By investing in these students, NIC and Welltower are helping to build the next generation of senior housing professionals. 

Former NIC Conference Scholar, Kate Abate, reflects on her experience attending the 2022 NIC Fall Conference and the career opportunities it provided.  

As a mid-career student graduating from the USC Leonard Davis School of Gerontology, I understood the value relationships could make with respect to career growth. Half of the battle is showing up. The other half may just as well be showing up to the right room. 

When I learned I had the opportunity to be nominated for the NIC Scholar Program, I did everything I could to secure my place, including reaching out to NIC Co-founder and Strategic Advisor, Bob Kramer, after hearing him speak in a class. I asked for advice on pursuing what seemed like a rare opportunity: becoming involved with New York’s first university-based retirement community. He said, “Absolutely—innovation is the future.” That set me in motion. 

Having studied the seniors housing field, I knew many of the leaders I admired would be attending the 2022 NIC Fall Conference. Bob confirmed my belief that it was the place to be. If I was fortunate enough to be there, I wanted to arrive prepared. I researched attendees, studied the conference agenda, and familiarized myself with the organizations and communities represented. My goal was simple: learn from the very best. 

The experience exceeded every expectation. 

I reached out to CEOs, developers, and operators whose work I admired and asked if they would spare fifteen minutes to share career advice. I was surprised not only by how many said yes, but by their genuine interest in helping someone just entering the profession. Equally memorable was the way the NIC team welcomed and stewarded the Scholar cohort. We were treated as future contributors to the field, and that confidence inspired me to show up fully. 

The energy was palpable. 

The defining moment came late on the second day of the conference. I learned that Joel Nelson, founder of LCS, the company developing Broadview at Purchase College, would be in the lobby in just a few minutes. I introduced myself and shared my enthusiasm for the university-based retirement community model and my hope of contributing to the Broadview project. He encouraged my interest and told me he would see what might be possible. 

The next morning, I woke up to emails from Joel Nelson and Ashley Wade, Broadview’s first Executive Director, inviting me to begin the conversation about joining the project. 

That opportunity became the foundation of the next chapter of my career. During the following three years, I had the privilege of helping launch and stabilize Broadview, an experience that shaped not only my professional path, but also my understanding of leadership, innovation, and purpose in seniors housing. 

One piece of advice from Bob Kramer has stayed with me ever since. After encouraging me to pursue Broadview, he simply said, “And take notes.” 

I did. 

My advice to future Scholars is equally simple: prepare before you arrive, introduce yourself, ask thoughtful questions, and take notes. The relationships you build and the conversations you have may shape your career in ways you cannot yet imagine. 

For me, they certainly did. 
Senior Housing Faces an Estimated Trillion-Dollar Supply Gap as Demographic Wave Arrives 

The U.S. senior housing sector is entering what NIC MAP’s latest Market Outlook Report calls the steepest stretch of 80+ population growth in the nation’s history — and the industry’s current pace of construction isn’t close to keeping up. 

A Demographic Wave with Certainty 

The first Baby Boomers turned 80 in 2026, kicking off a demographic shift that is unusually predictable: because it’s based on census counts of people already alive rather than economic forecasts, the timing and scale are essentially locked in. The 80+ population is projected to grow by a third by 2030, two-thirds by 2035, and nearly double by 2040 — adding roughly 5 million people over 80 within five years and 13 million within fifteen. 

That growth is already showing up in operating data. Senior housing occupancy has risen more than 200 basis points in each of the last four consecutive years — a streak not observed in any other major commercial real estate property type over the same period. Annual net absorption has averaged 32,000 units since 2022, about 50% above the pre-2020 record of under 22,000 units, and every quarter since 2022 has topped the strongest pre-pandemic period on record. 

Construction Has Not Kept Pace 

While demand for senior housing has increased, new construction has moved in the opposite direction. Senior housing construction starts have fallen every year since 2021, dropping 67% to roughly 10,000 units in 2025 — a level last seen after the 2008 financial crisis. The causes mirror those across commercial real estate broadly: high interest rates, elevated construction costs, and labor constraints. Senior housing carries an added headwind: operating margins, while recovering, remain below pre-2020 levels, so many projects that penciled out in 2019 still don’t work financially today. 

The result is a widening gap. In 2022, 80+ population growth overtook senior housing inventory growth for the first time this decade, and NIC MAP projects that gap will continue widening through 2030, with population growth approaching 7% annually against inventory growth near 1%. 

A Multi-Decade, Trillion-Dollar Build-Out 

To hold national occupancy at 90% as the population ages, NIC MAP’s model shows the industry needs to deliver more than 100,000 new units in most years between 2025 and 2035 — with a spike above 141,000 units required in 2027 alone. The current development pace of roughly 10,445 units a year covers only a fraction of that. Even the industry’s highest-ever 12-month total this century, 56,145 units, would cover only about half of a typical year’s need. 

Left unaddressed, the shortfall compounds: the cumulative gap between required and actual deliveries grows from about 60,000 units in 2025 to nearly 600,000 by 2030 and over 1 million units by 2035. Translated into dollars, the capital required to maintain today’s penetration rate is forecasted to exceed $1 trillion by 2050 — with the large majority of that need sitting above what current investment levels would supply. 

Capital markets appear to be taking notice: senior housing led all major property types in one-year total returns on the NCREIF index, and 2025 transaction volume topped $15 billion, an industry record. But translating that renewed investor interest into actual new supply — through ground-up development, campus expansion, and repositioning — remains the central challenge facing the sector over the next two decades. 

For more in-depth details and insights, we encourage readers to access the NIC MAP Senior Housing Market Outlook – Second Edition report.  

Active Adult Occupancy Up as Development Slows 

NIC MAP released third quarter data for the 880 active adult rental communities they track across the U.S. Active adult communities are age-eligible, market-rate, multifamily rental properties focused on enhanced lifestyle programming without providing meals. 

Key takeaways included the following:  

Takeaway #1: Pace of Active Adult Development Has Slowed 

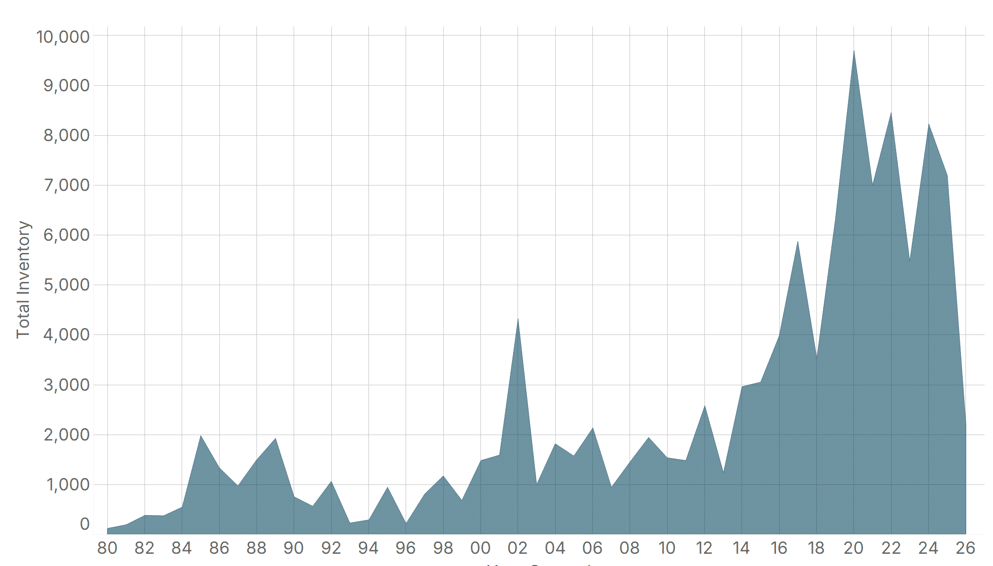
  • The chart below illustrates active adult rental inventory by the year these properties opened. 
  • Active adult is still a relatively new product type, with roughly half of inventory opened in the past 10 years. 
  • In the first three quarters of 2026, however, NIC MAP tracked only 2,200 new units opening across 880 active adult rental communities comprised of nearly 130,000 units. 
  • This pace is well below recent years in which openings averaged 7,000 new units per year over the 2023 through 2025 period.  

Takeaway #2: Active Adult Occupancy Rates Climbed Higher 

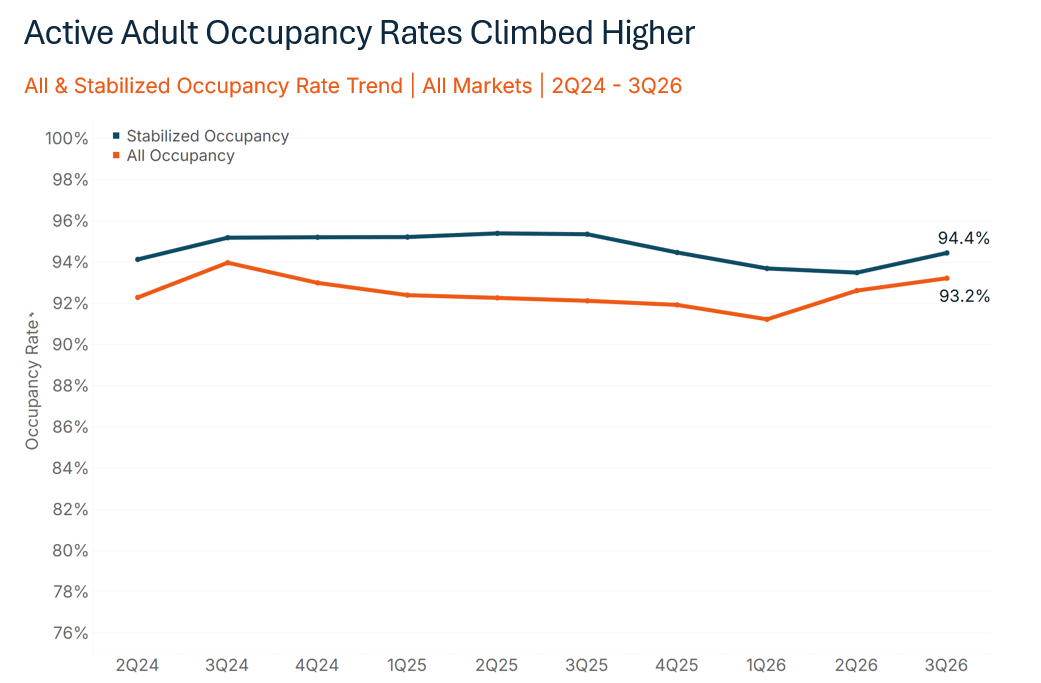
  • Against this backdrop of slower supply growth, the average active adult occupancy rate increased 0.6 percentage points in the third quarter to 93.2%, up 1.3 percentage points so far in 2026. 
  • For stabilized properties open at least two years, occupancy rates jumped by 0.9 percentage points to 94.4%, roughly in line with where they started the year. 

Takeaway #3: Active Adult Occupancy Rates Improving in Sunbelt and Other Select Markets 

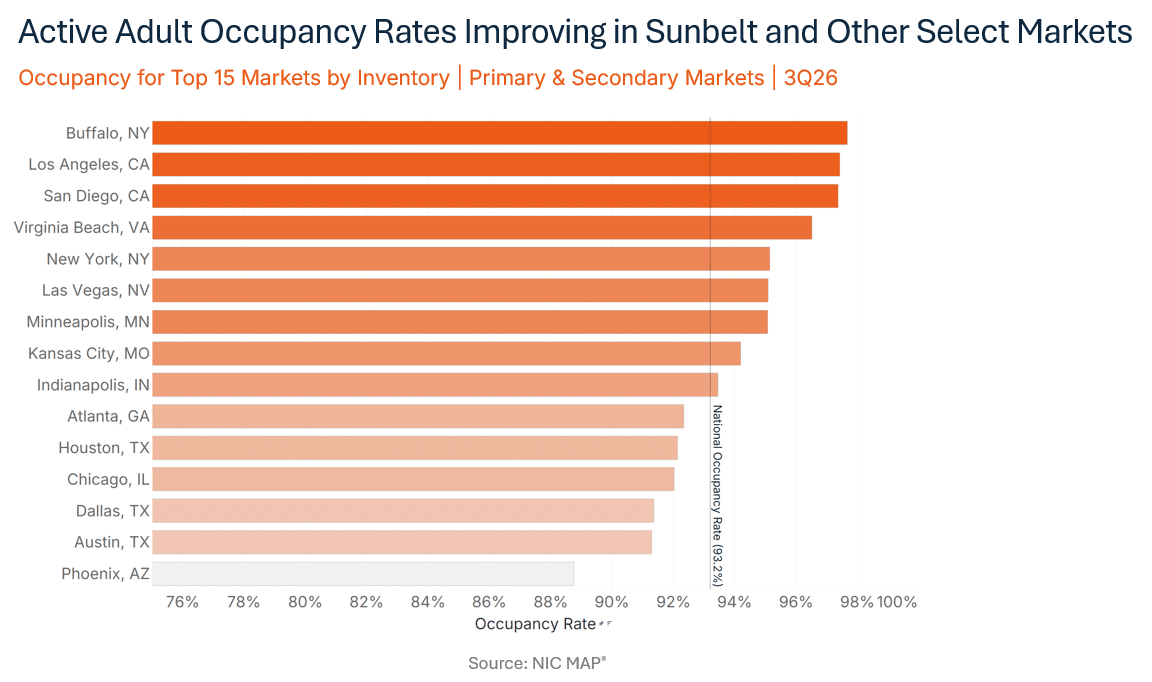
  • For the 15 largest active adult rental markets, the bar chart below shows All Occupancy rates, with the U.S. average of 93.2% shown in the dotted line. 
  • The highest occupancy rates in the third quarter were in Buffalo (97.7%), Los Angeles (97.4%), and San Diego (97.4%).  
  • Phoenix had the lowest occupancy rate at 88.7%. Austin ranked second lowest but had a significant improvement of 3.3 percentage points from the prior quarter to 91.3% in the third quarter.  
  • These trends may indicate that some of the softening in the active adult market in 2025 has improved in 2026. 

Takeaway #4: Most Popular Active Adult Amenities Focus on Lifestyle and Wellness 

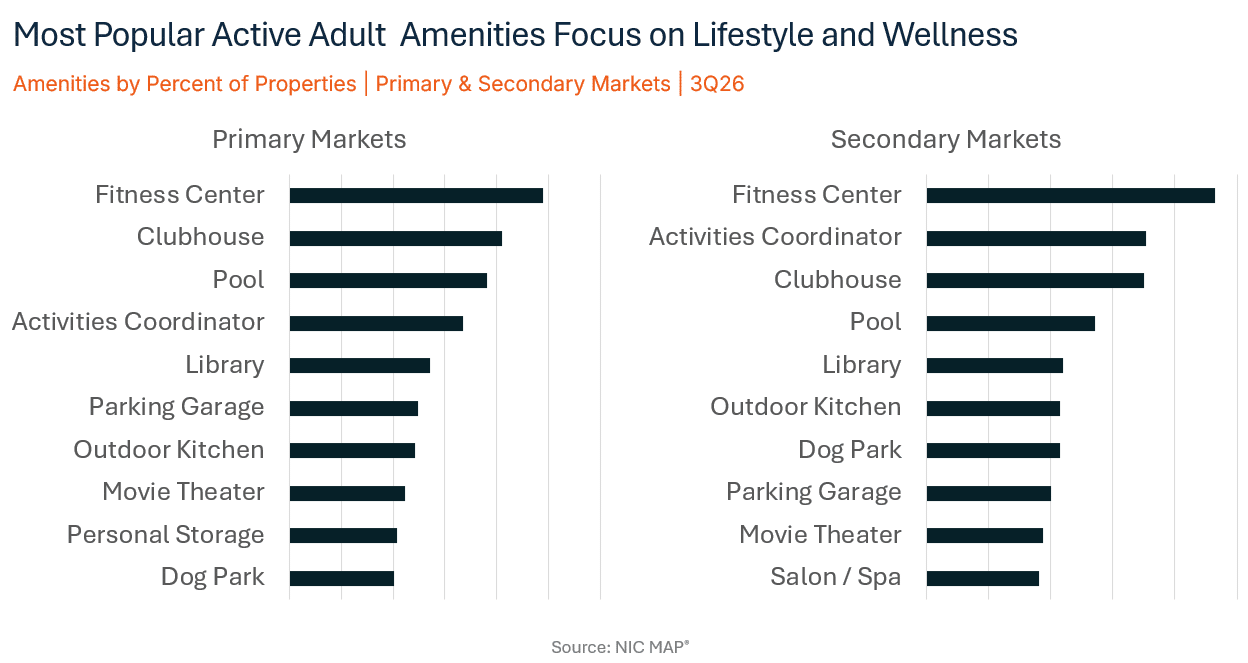
  • Below are the top ten amenities ranked by percent of active adult properties in the third quarter. 
  • Fitness centers, clubhouses, pools, and activities coordinators were most popular within both the Primary and Secondary Markets, highlighting the focus on lifestyle, wellness, and engagement that appeal to active adult residents. 

Senior Housing Occupancy Nears Record High as Primary Markets Surpass 90%  

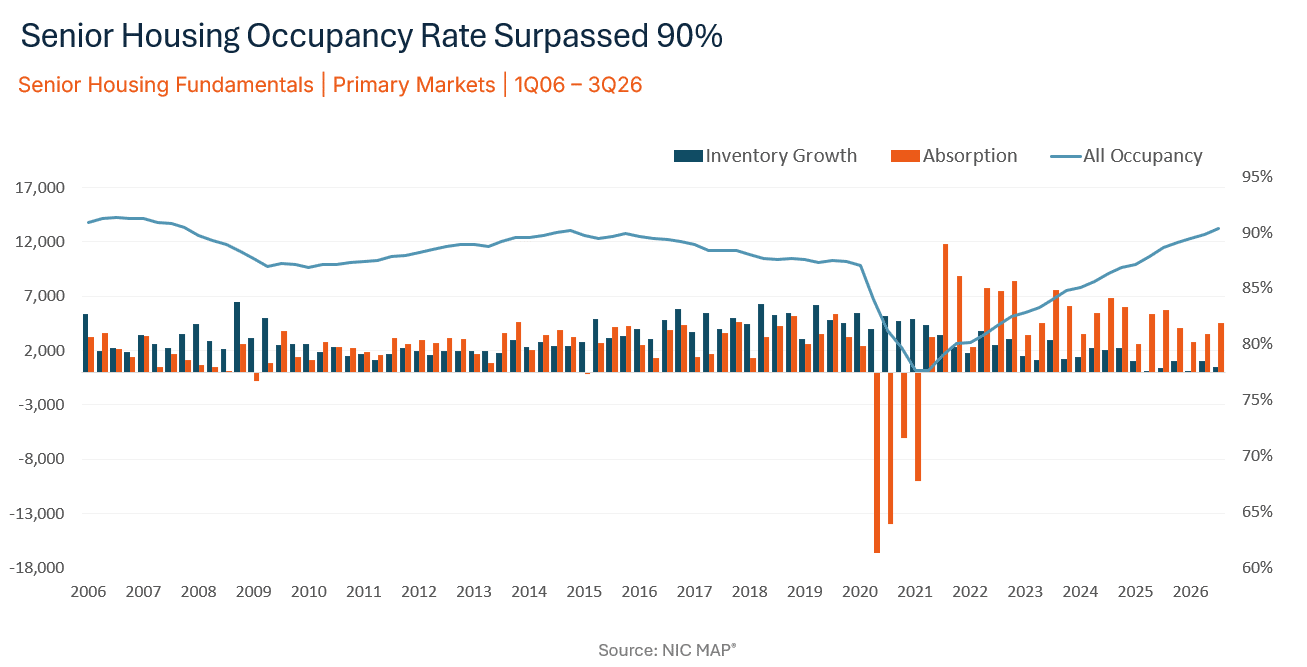
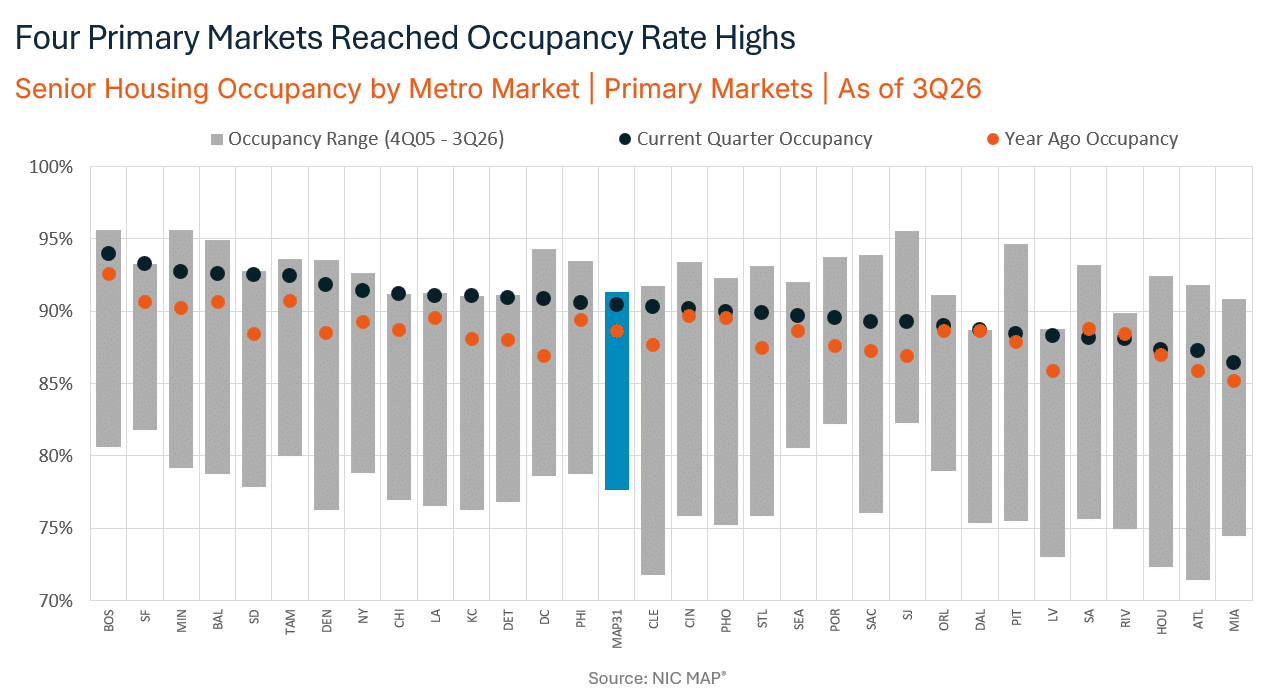
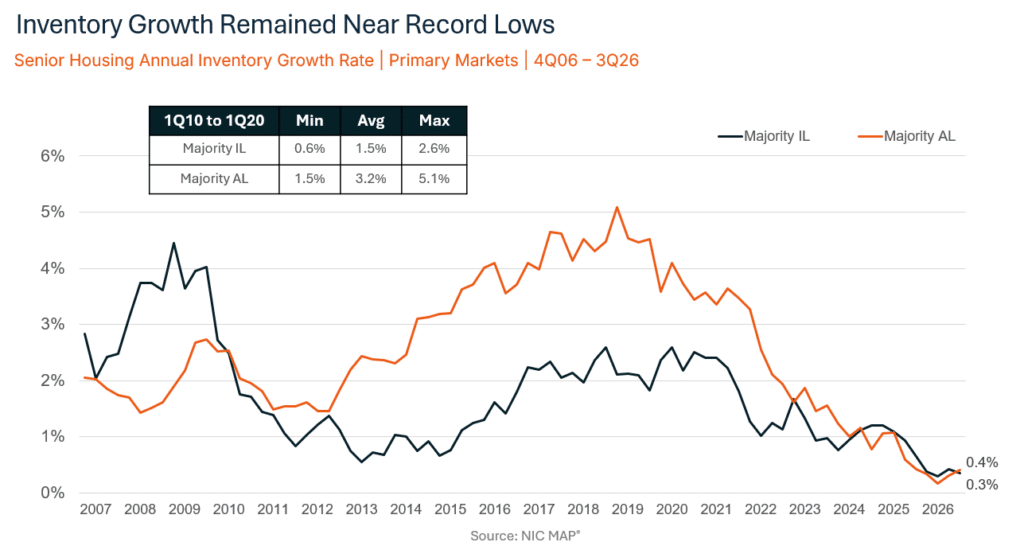
Senior housing occupancy surpassed 90% in the third quarter, the first time that primary market occupancy rates have been above 90% since 2014. Occupancy rates reached record highs in four primary markets – San Francisco, Chicago, Kansas City, and Dallas. At the same time, inventory growth remained near record lows, measuring below 1.0% for the sixth consecutive quarter. 

These and other findings on quarterly senior housing data trends were presented by NIC’s Research & Analytics team during a recent webinar with NIC MAP clients.  Joe Daniel, Vice President, Direct Supply, joined Lisa McCracken, NIC’s Head of Research, on the webinar to discuss industry trends related to the development pipeline activity. 

Key takeaways included the following:  

Takeaway #1: Senior Housing Occupancy Rate Surpassed 90% 

  • The occupancy rate for senior housing rose 0.6 percentage points in the third quarter for the 31 NIC MAP Primary Markets to reach 90.4%, driven by positive net absorption outpacing the number of new units arriving online. 
  • The third quarter of 2026 marked the first time that occupancy rates have been above 90% since 2014. 

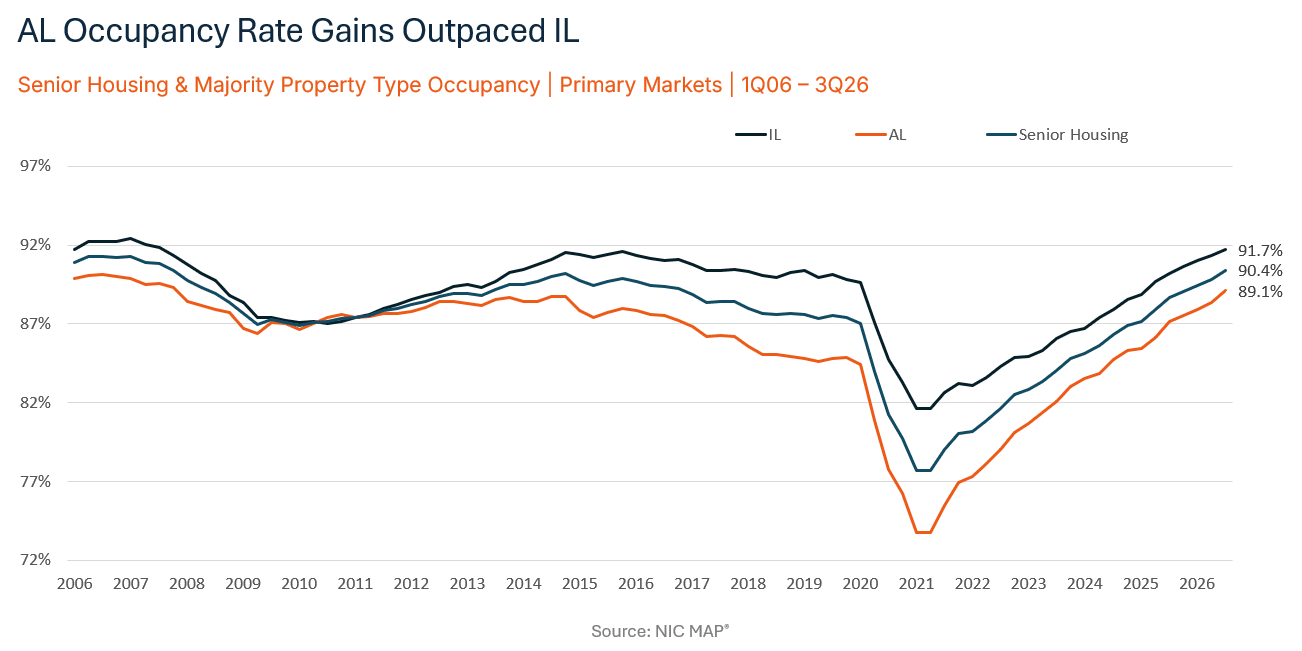
Takeaway #2: Assisted Living Occupancy Rate Gains Outpaced Independent Living 

  • Breaking out occupancies by property type, the occupancy rate for independent living communities rose 0.4 percentage points in the third quarter to reach 91.7%, while the occupancy rate for assisted living communities rose twice as fast, increasing by 0.8 percentage points to reach 89.1%. 
  • As a result of assisted living gains outpacing those of independent living, the gap between the two occupancy rates narrowed to only 2.6 percentage points in the third quarter, which was the smallest spread between the property type occupancies since 2014. 

Takeaway #3: Four Primary Markets Reached Occupancy Rate Highs 

  • There are four markets where occupancy rates today have reached their time series highs – San Francisco (93.3%), Chicago (91.2%), Kansas City (91.1%), and Dallas (88.7%) – and four additional markets that are within just 50 basis points or less of reaching their historical highs. 
  • Overall, 17 of the 31 Primary Markets (55%) had occupancy rates at or above 90% in the third quarter. 

Takeaway #4: Inventory Growth Remained Near Record Lows 

  • Turning to new supply, year-over-year inventory growth remained below 1.0% for the sixth consecutive quarter and near the time series low. 
  • Breaking out supply by property type, independent living inventory increased 0.3% from a year earlier, well below its historical average growth of 1.5% annually. 
  • Assisted living inventory increased only 0.4% from a year earlier, well below its historical average growth of more than 3% annually. 

The Margin Test: Is Strong Senior Housing Occupancy Translating into Operating Performance? 

In The Great Tightening article, we showed how senior housing has led major commercial real estate sectors in year-over-year occupancy growth for four consecutive years, while an increasing share of properties are operating at high occupancy levels. But as the sector moves toward a tighter market, are those occupancy gains translating into stronger operating margins across properties? 

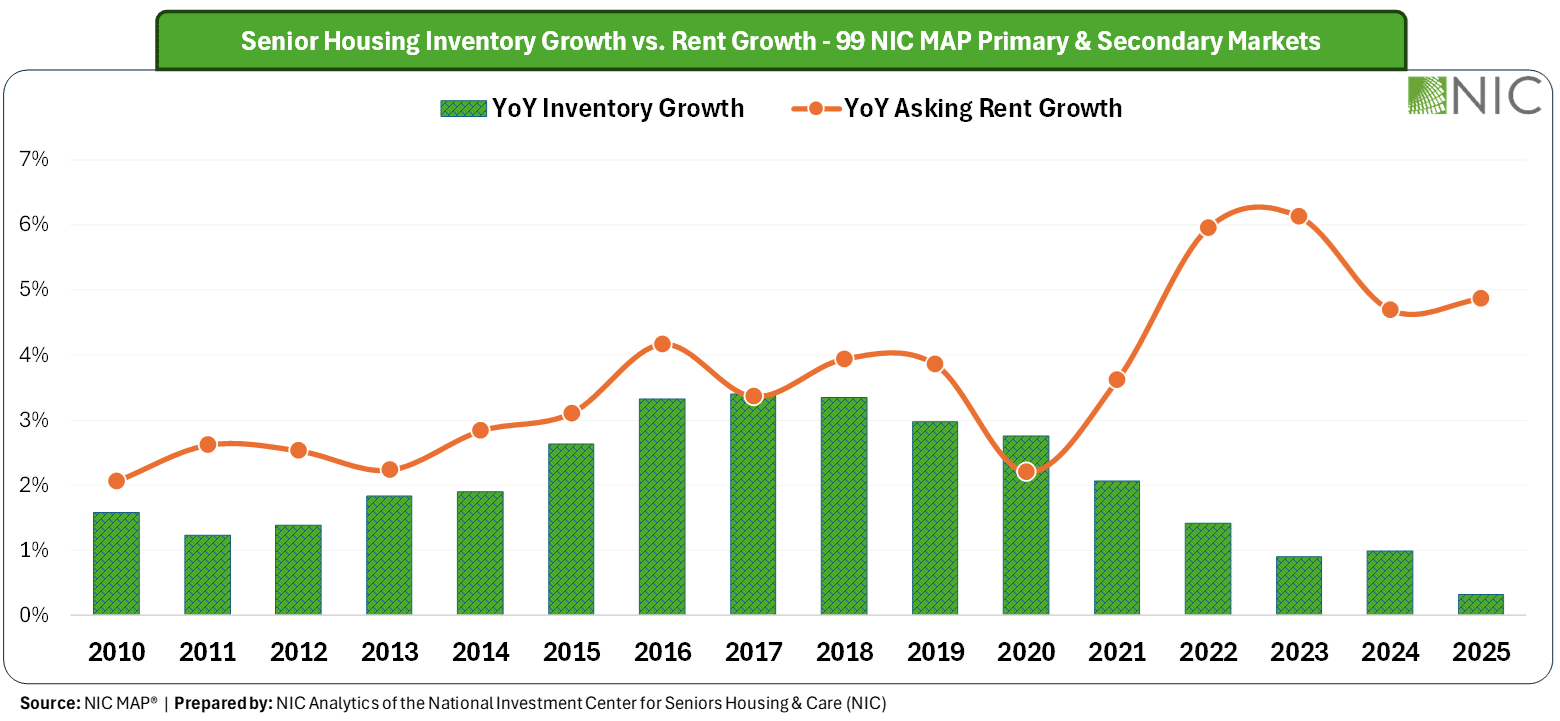
A Break Between Supply Growth and Rent Growth 

For much of the decade before the pandemic, senior housing inventory growth and asking rent growth moved within relatively narrow ranges. Year-over-year inventory growth generally ranged between roughly 1% and 3%, while asking rent growth remained largely between 2% and 4%. The two measures did not move perfectly together, but neither broke away from its historical range for an extended period. 

In recent years, the relationship has changed. Inventory growth slowed sharply after the pandemic and continued to decelerate, reaching historically low levels by 2025. Asking rent growth moved in the opposite direction, accelerating above 4% in 2022 and remaining above that threshold through 2025. 

Part of the initial acceleration in asking rents coincided with unusually high inflation, rapidly rising operating costs, and subsequent interest rate increases by the Federal Reserve. Labor, food, utilities, insurance, and other expenses placed notable pressure on operators, making higher rates increasingly necessary to offset rising costs. 

What is more notable is what happened next. As inflation moderated, senior housing asking rent growth did not return to its pre-pandemic range. Although, pricing dynamics vary considerably across markets, segments, and properties. 

Historically low inventory growth, higher occupancy and asking rent growth would seem to create a powerful backdrop for operating performance. Yet a look at property-level margins shows that the effects have not flowed through evenly. 

Higher Rents Have Not Produced a Margin Breakout 

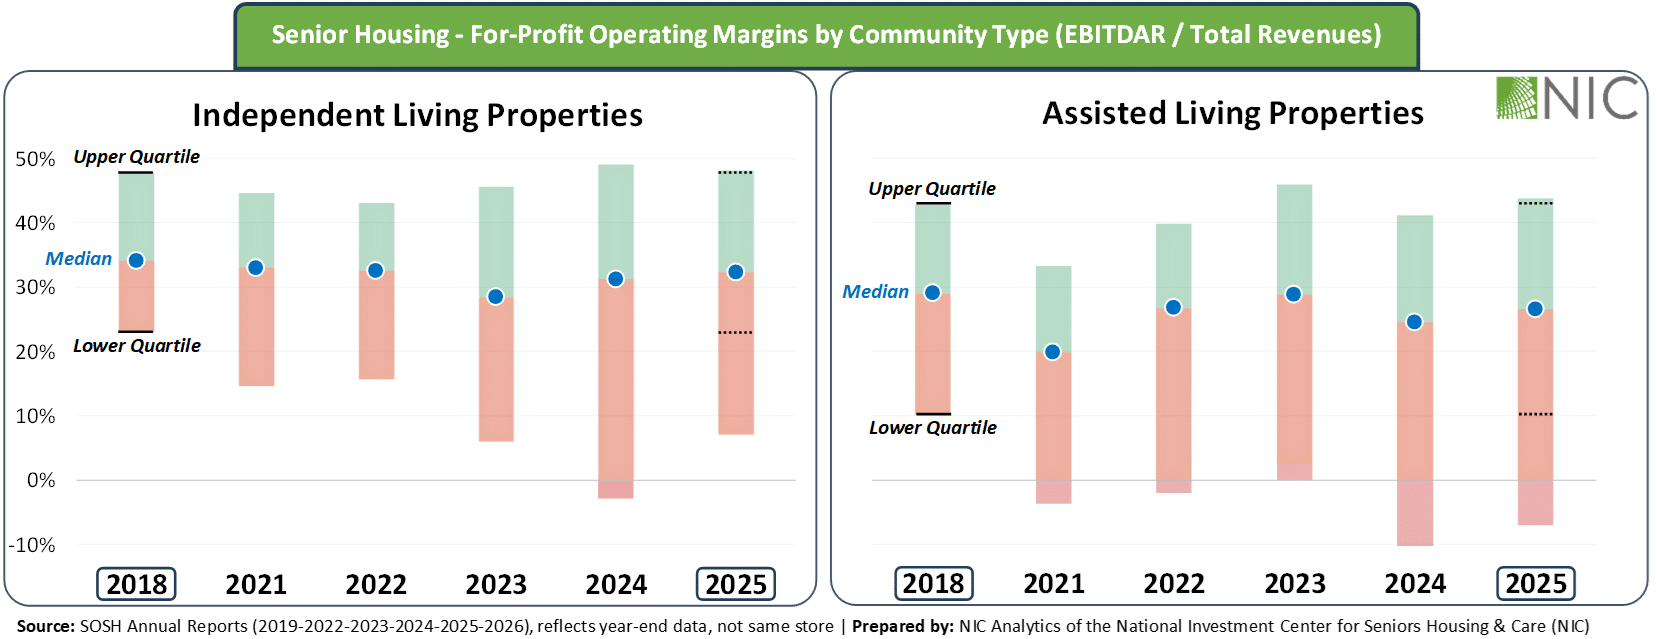
If the first chart tells a story of stronger rent growth, the second introduces an important counterpoint. Median operating margins have somewhat recovered, but they have not experienced the same post-pandemic pattern as asking rent growth. 

For for-profit independent living properties, the median EBITDAR margin in 2025 was roughly in line with its 2018 pre-pandemic benchmark. Assisted living followed a more volatile path, experiencing a much sharper decline in 2021 before recovering toward its 2018 median by 2025. 

Assisted living is more labor- and care-intensive than independent living, making its financial performance particularly sensitive to staffing costs and other operating expenses. Labor remains the largest expense in senior housing and can weigh on NOI even as revenue grows. 

The data suggest that at least some of the rent growth of recent years may have been needed to absorb higher operating costs rather than expand margins. That would help explain why asking rent growth moved well above its historical range while median operating margins largely recovered to, rather than materially exceeded, pre-pandemic levels.  

The Median Is Only Half the Story 

Perhaps the more revealing finding is the distribution around the median. By 2025, median operating margins for both independent living and assisted living had moved back toward their 2018 benchmarks. Yet the gap between the upper and lower quartiles is considerably wider than it was in 2018. 

In independent living, in 2025, the lower quartile remains below its 2018 level even as the upper quartile approaches 50% margin. The 2025 dispersion is even wider in assisted living, where the lower quartile remains negative while the upper quartile exceeds 40% margin. 

The median may have recovered, but the operating recovery has not been uniform. Properties can operate within the same favorable demand environment and produce very different financial outcomes, although there is no single national operating environment. Strong occupancy and pricing can provide a tailwind, but labor management, expense control, property positioning, local market conditions, state-level differences in reimbursement, managed care, physical plant, and operator execution still matter. 

Senior housing is, after all, both real estate and an operating business. And as occupancy rises, that distinction becomes more important, not less. 

From the Occupancy Recovery to the Margin Test 

The margin test will not be the same for every property. And that is why the industry’s transition from recovery to tightening represents more than an occupancy story. 

As properties become increasingly full, the drivers of incremental performance begin to change. Strong occupancy tells us how tight the market has become, but what it means for operating performance depends on what happens at the property level, especially where incremental occupancy can be absorbed without a proportional increase in operating costs. That operating leverage is the margin test.