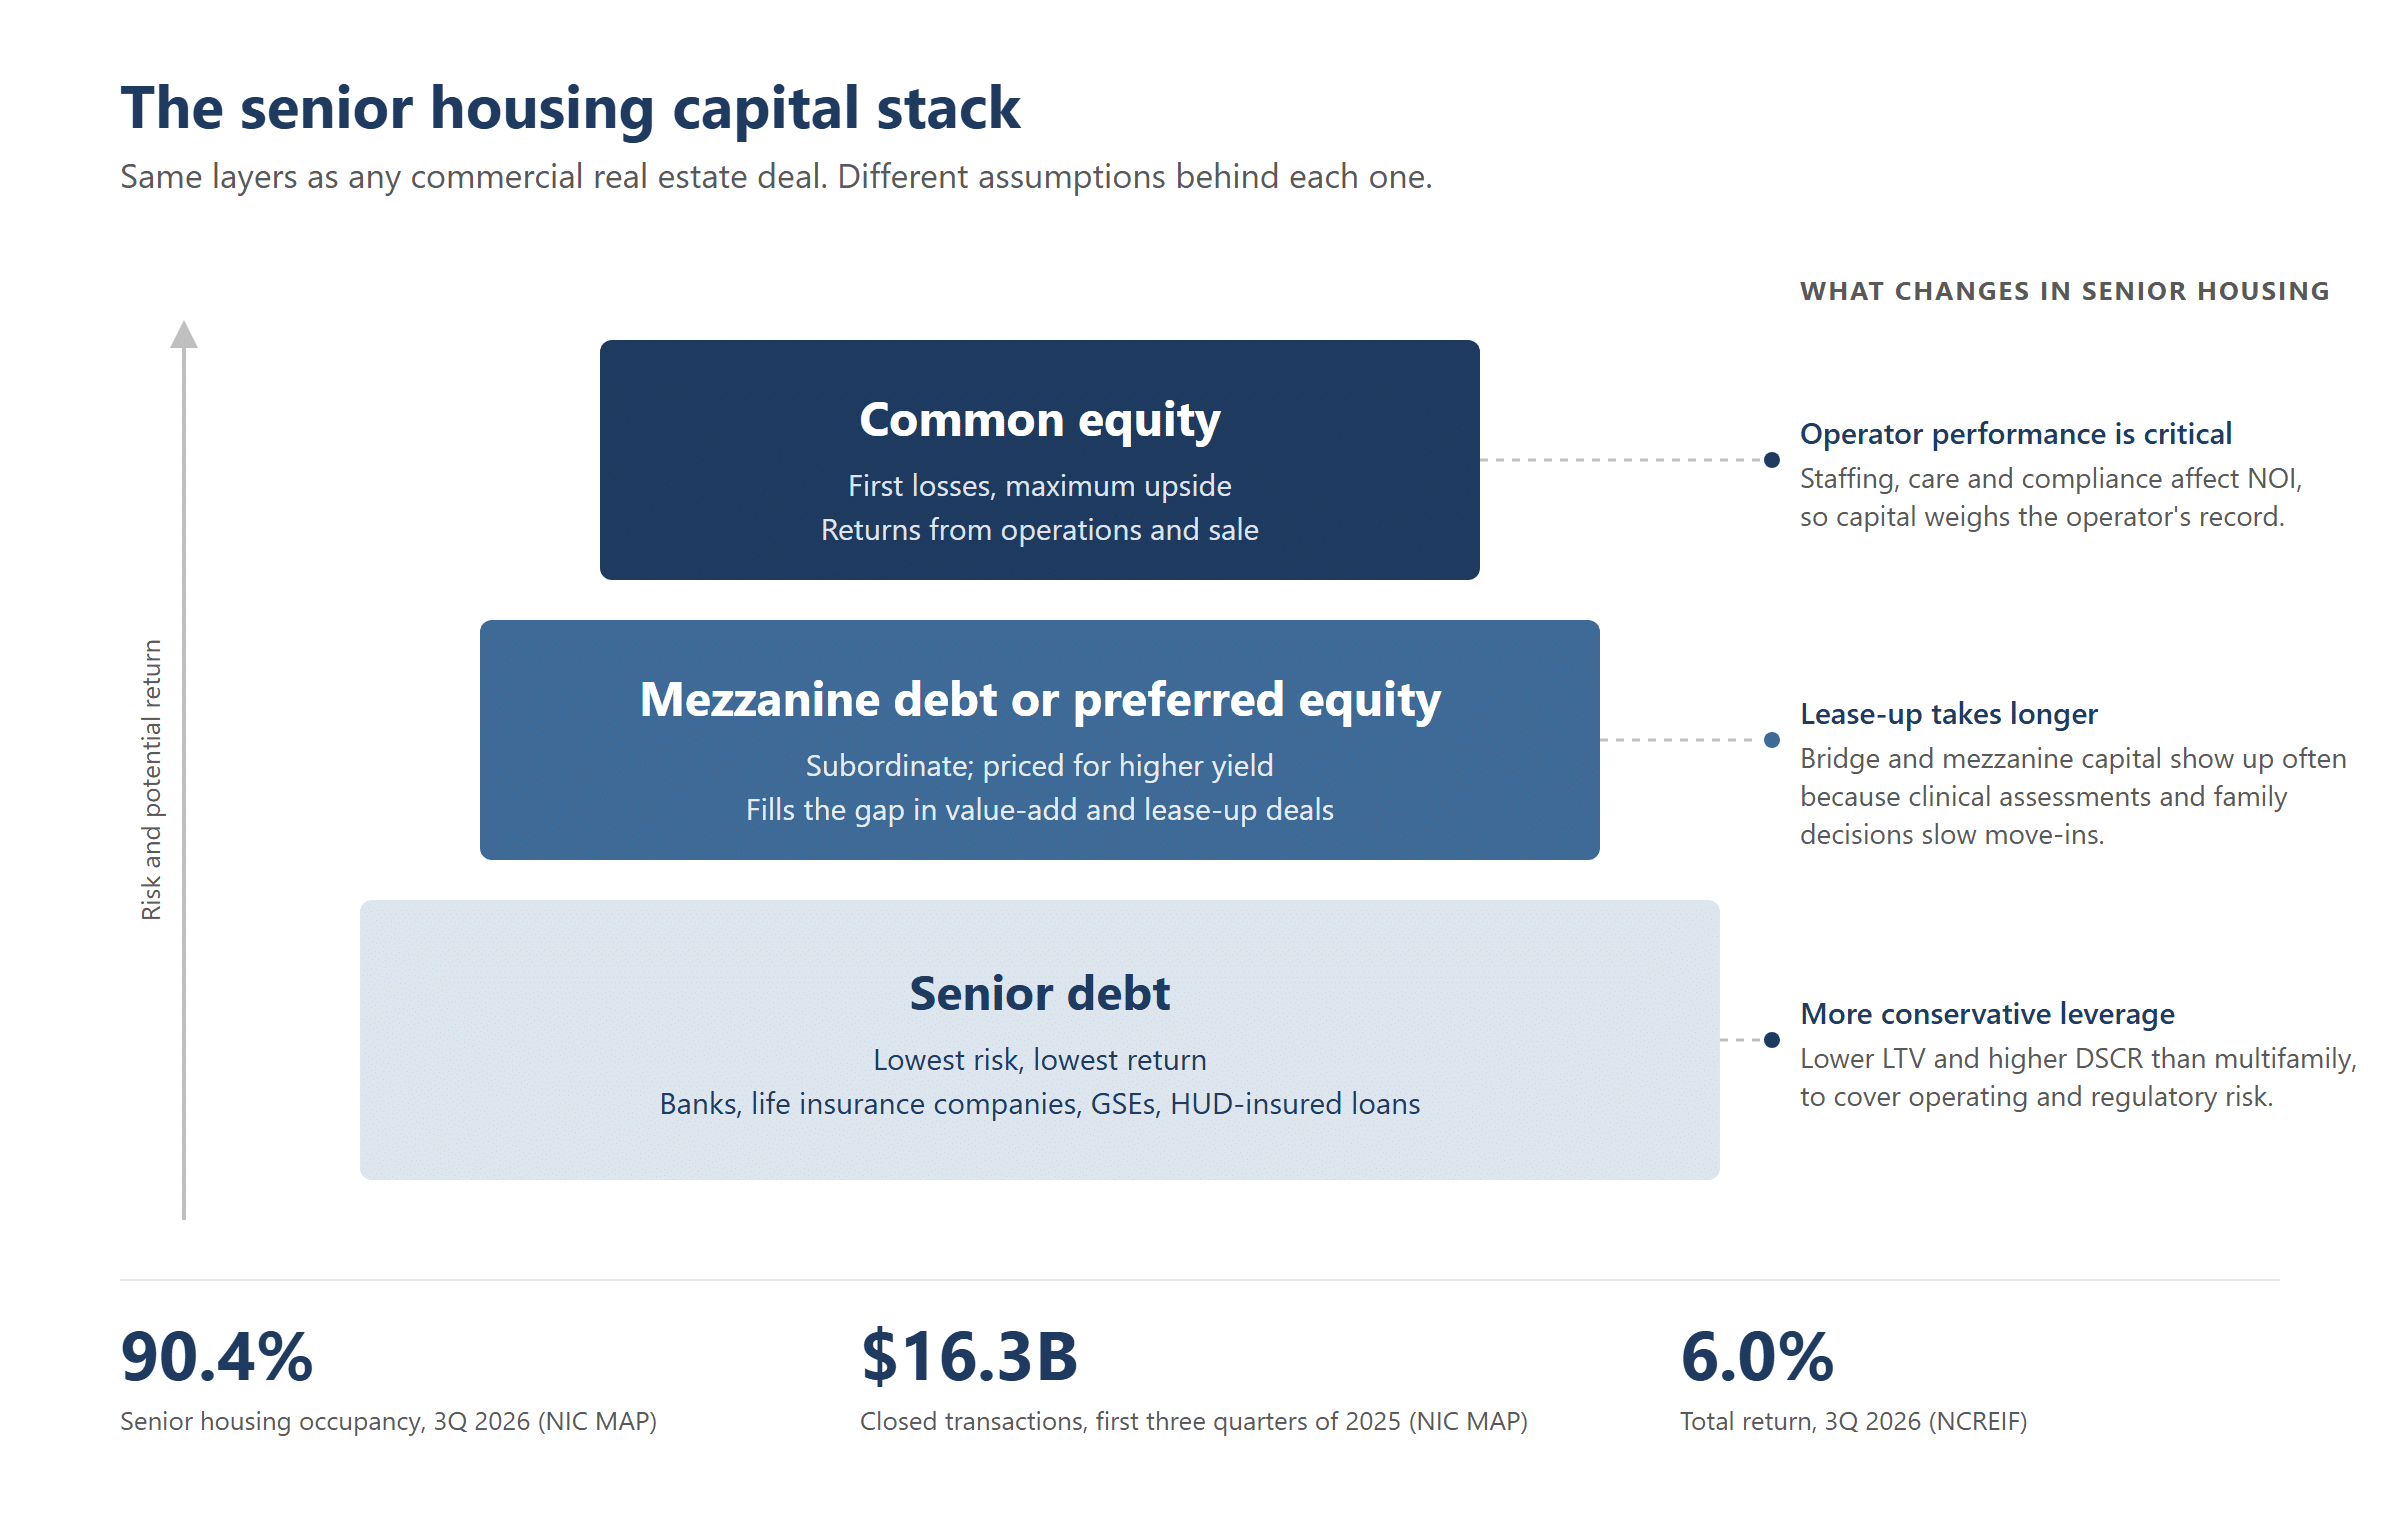
Commercial real estate investment is typically financed through a capital stack, layered by risk and return. Senior debt provides the foundation. Mezzanine debt or preferred equity may fill the gap, and common equity absorbs the greatest risk in exchange for the greatest potential return. Investors familiar with multifamily, office, or industrial properties will recognize the structure immediately.
Senior housing follows the same framework, but the factors that determine risk and return differ in important ways. Because these investments combine a real estate asset with an operating business, lenders and equity partners evaluate more than occupancy and rental income in their underwriting process. Staffing, regulatory oversight, operator performance, and local market conditions all shape how capital is structured and priced.
Understanding what makes senior housing financing unique is essential for anyone entering the sector. The capital stack itself may look familiar, but the assumptions behind each layer change once resident care becomes part of the equation.
The Capital Stack Basics: What Remains the Same
The three primary layers of a senior housing capital stack mirror those typically found across commercial real estate.
Senior Debt
- Risk Profile: Lowest-risk layer, offering the lowest-return position.
- Capital Sources: Commercial banks, life insurance companies, finance companies, government-sponsored enterprise (GSE) programs, and HUD-insured financing.
- Underwriting Nuance: Loan-to-value (LTV) ratios are generally more conservative than conventional multifamily because lenders must account for specialized operating risks.
Mezzanine Debt and Preferred Equity
- Risk Profile: Subordinate in the repayment structure, requiring higher yield returns to justify the risk.
- Primary Use Case: Highly common in value-add acquisitions and local lease-up projects where current occupancy has not yet stabilized enough to support maximum senior debt proceeds.
Common Equity
- Risk Profile: Sits at the top of the stack, absorbing first losses but capturing maximum upside.
- Return Drivers: Profits flow from operating distributions and long-term asset appreciation upon sale.
The Lease-Up Hurdle
In senior housing, reaching stabilized occupancy depends on many more factors than standard apartment leasing.
Familiar underwriting metrics like LTV (Loan-to-Value), DSCR (Debt Service Coverage Ratio), preferred return hurdles, IRR (Internal Rate of Return), and equity multiples remain standard. However, the inputs behind them shift dramatically.
Debt service coverage depends on Net Operating Income (NOI). In this asset class, NOI reflects a blend of real estate fundamentals and active operational performance.
Where Senior Housing Finance Differs: Navigating Operating Risks
The defining characteristic of senior housing investment is that investors are evaluating both a real estate asset and an operating business.
The Operating Company (OpCo) Structure
Unlike multifamily or office properties, revenue depends on more than physical occupancy. A licensed operator must successfully recruit and retain staff, manage clinical resident care, and maintain strict compliance.
Many transactions separate the real estate from operations using a RIDEA structure or a master lease. Each structure allocates operating risk differently between the owner (PropCo) and the operator (OpCo), making the operator’s track record a primary underwriting factor.
Reimbursement and Payor Mix Risks in Senior Housing
Independent living and most assisted living communities rely heavily on private-pay revenue.
Conversely, skilled nursing often depends on government reimbursement through Medicare and state-administered Medicaid. This introduces an additional layer of policy and regulatory payment risk. As exposure to government reimbursement increases, lenders typically tighten underwriting assumptions.
The Specialized Lease-Up Timeline
Lease-up curves for senior housing and care properties look vastly different from those of traditional multifamily assets. New resident onboarding can require clinical assessments, family consultations, and care coordination.
Because local occupancy builds gradually, lenders frequently mandate seasoning periods or strict occupancy thresholds before advancing secondary tranches of capital. This explains why mezzanine financing and bridge capital appear frequently in these transactions.
State-Level Regulatory Oversight
Senior housing communities operate under stringent state licensing requirements. Licensure status, compliance history, and survey performance are core components of due diligence, loan covenants, and equity agreements.
How Capital Structures Change Across Deal Types
While every transaction uses the same basic capital framework, financing profiles adapt based on the asset’s lifecycle phase.
- Stabilized Acquisitions: A stabilized private-pay community with strong historical occupancy supports traditional financing. Conservative senior debt provides the bulk of the stack, while common equity supplies the balance.
- Value-Add Acquisitions: Communities experiencing operational turnarounds or below-market occupancy routinely require mezzanine debt or preferred equity. This bridging capital fills the gap until performance improves enough to refinance via lower-cost senior debt.
- Ground-Up Development: Carrying the highest risk profile, construction loans feature lower loan-to-cost (LTC) ratios, mandatory completion guarantees, and larger equity requirements.
Local Underwriting Trends and Market Data Impact
Every financing decision relies on confidence in future NOI. Estimating these figures requires local market data showing current occupancy, absorption trends, competitive supply, and local development pipelines.
Unlike multifamily, where simple rent comparables drive the model, senior housing requires market-specific operating data, closely segmented by care level and geography. These regional figures dictate occupancy projections, revenue assumptions, and pricing within the capital stack.
Macro Performance Metrics
- Occupancy: In the third quarter of 2026, national senior housing occupancy reached 90.4%, driven by an aging population and inventory growth remaining near historic lows.
- Strong Demand Signals: According to NIC MAP, closed transaction volume in senior housing and nursing care reached $16.3 billion through the first three quarters of 2025, with senior housing acquisitions accounting for over $10.3 billion.
- Return Benchmarks: Senior housing posted a 6.0% NCREIF total return in the third quarter of 2026, triple the next-highest property type and its eighth straight quarter ahead of the NCREIF Property Index.
Despite strong fundamentals, regional lending standards remain highly disciplined. Lower LTV ratios and elevated DSCR requirements mean macro and micro-market fundamentals dictate how a deal gets structured.
Securing Your Capital Structure
The senior housing capital stack uses familiar commercial components: senior debt, mezzanine financing, preferred equity, and common equity. What sets it apart is the operating business inside the real estate.
Sound underwriting begins with localized market data. CSHIP Level I works through real deals and case studies; request information to find the level that fits your role.