The CMS Advancing Chronic Care with Effective, Scalable Solutions (ACCESS) model launched this summer, covering chronic conditions across four tracks. Participation spans cardiometabolic and kidney care, behavioral health, musculoskeletal care, and chronic pain management—signaling continued demand for technology-enabled, outcomes-based chronic-care solutions.
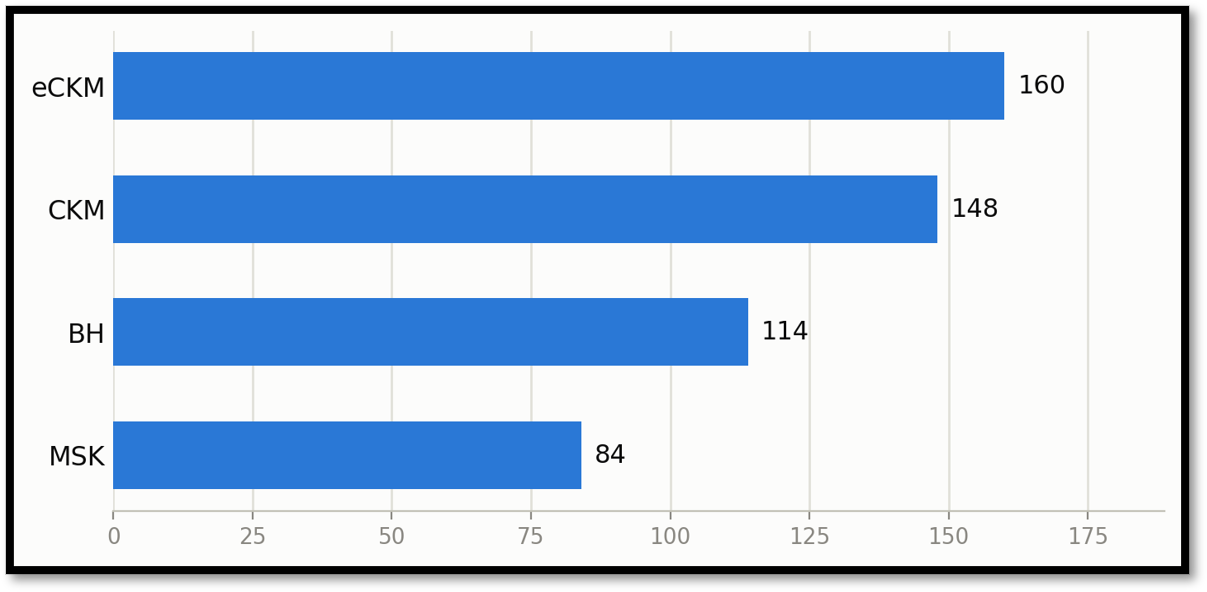
The 205 participating organizations may participate in one or more clinical tracks: eCKM, CKM, MSK, and BH. Because organizations can enroll in multiple tracks, an organization participating in more than one track is counted once in each applicable track in the graph below. CMS is expected to provide additional information in October, including updates on participating organizations and newly joining companies.
CMS is using small, partial payments to drive outcomes. Every ACCESS participant, in effect, is fronting the cost of care today against a resident outcome realized months later.
Participants include: Artificial Intelligence (AI)-first companies, Accountable Care Organizations (ACOs), traditional healthcare operations and practices and digital healthcare organizations. Those that succeed and scale over time will be a signal, both to the market and to CMS.
Senior housing and care operators can expect technology, and interoperability will be increasingly relevant to residents, particularly those with high acuity conditions covered in these tracks. They may be moving in with these services ongoing, covered by health payors, and have high expectations for monitoring and evaluation support, in addition to needs for more traditional medication management services.
CMS is also expected to announce the first Make America Healthy Again: Enhancing Lifestyle and Evaluating Value-Based Approaches Through Evidence (MAHA ELEVATE) awardees this fall. The research model’s first round winners are expected to launch in October 2026 with the distribution of over $100 million in funds. The model is designed to evaluate whole-person and lifestyle-medicine interventions and their effect on Medicare cost and quality. Senior living was named among the model’s eligible applicants, and the fall announcement can inform how CMS is structuring an overall approach to this type of care. A second cohort in 2027 is expected as well, for those considering future applications.
Rate Growth Moderates for Independent Living and Assisted Living in 2Q 2026
Data from the recently released 2Q 2026 NIC MAP Actual Rate Report showed that:
Year-over-year growth across all rate categories for both independent living and assisted living properties continued to moderate in the second quarter of 2026, with notable deceleration compared with the prior quarter.
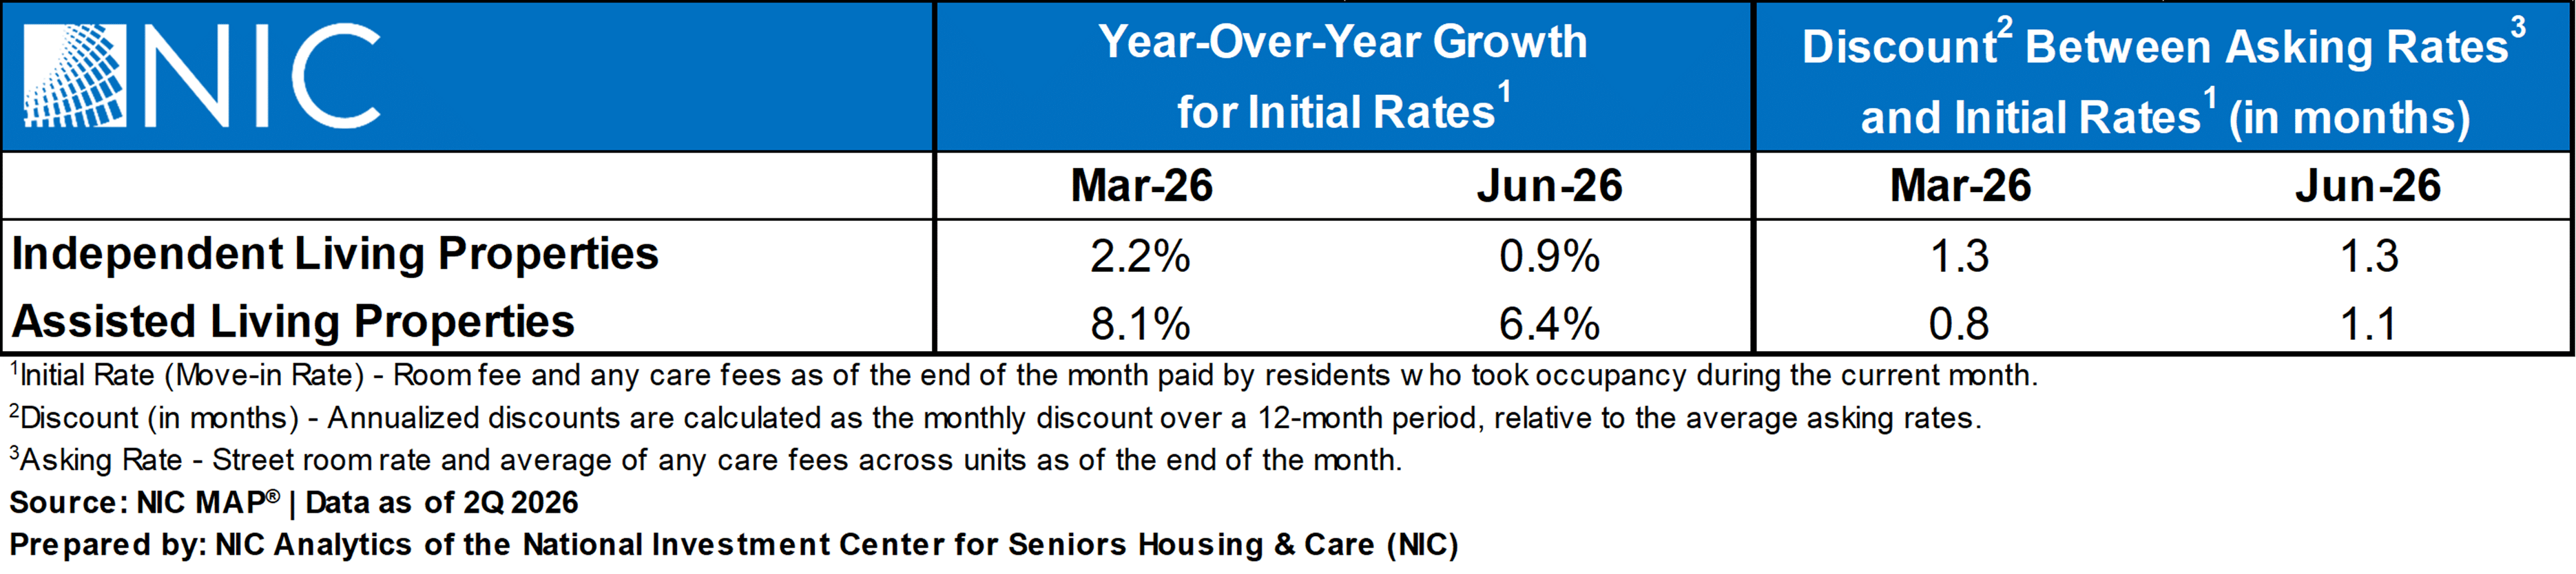
For independent living properties, year-over-year growth in in-place rates saw the largest deceleration, falling from 6.1% in March 2026 to 3.8% in June 2026. Asking rate growth moderated from 7.3% to 5.5%, while initial rate growth fell to just 0.9%, down from 2.2% in March 2026.
For assisted living properties, year-over-year growth in in-place, initial, and asking rates stood at 5.3%, 6.4%, and 5.3%, respectively, in June 2026. These rates represented a notable deceleration from March 2026, when growth in the three rate categories was 6.4%, 8.1%, and 7.1%, respectively.
The discount between asking and initial rates widened for assisted living properties in the second quarter of 2026, while the discount for independent living properties remained relatively unchanged.
For independent livingproperties, average initial rates were 11.0% ($534) below asking rates in June 2026, translating to a 1.3-month discount on an annualized basis, unchanged from March 2026.
Average initial rates for assisted livingproperties were 9.4% ($660) below asking rates in June 2026, equivalent to a 1.1-month discount on an annualized basis, up from the 0.8-month discount in March 2026.
Additional key takeaways are available to NIC MAP subscribers in the full report.
About the Report: The NIC MAP Seniors Housing Actual Rates Report provides aggregate national data from over 300,000 units within more than 2,800 properties across the U.S. operated by over 65 seniors housing providers. Visit the NIC MAP website for more information.
The Great Tightening: How Senior Housing Is Entering a New Occupancy Era
For much of the past five years, the senior housing story has been one of recovery. Quarter after quarter, occupancy climbed steadily from the unprecedented lows of the pandemic. Each NIC MAP data release marked another step toward normalcy, and each increase was viewed as evidence that the industry was regaining its footing.
That story has now run its course. The latest NIC MAP data showed that average senior housing occupancy across the 31 Primary Markets surpassed the 90% threshold in July 2026 a level the sector had previously reached only before the Global Financial Crisis and briefly again in late 2014. This milestone suggests that senior housing has entered an entirely different phase, one that is less about recovering lost ground and more about confronting the realities of a tightening market.
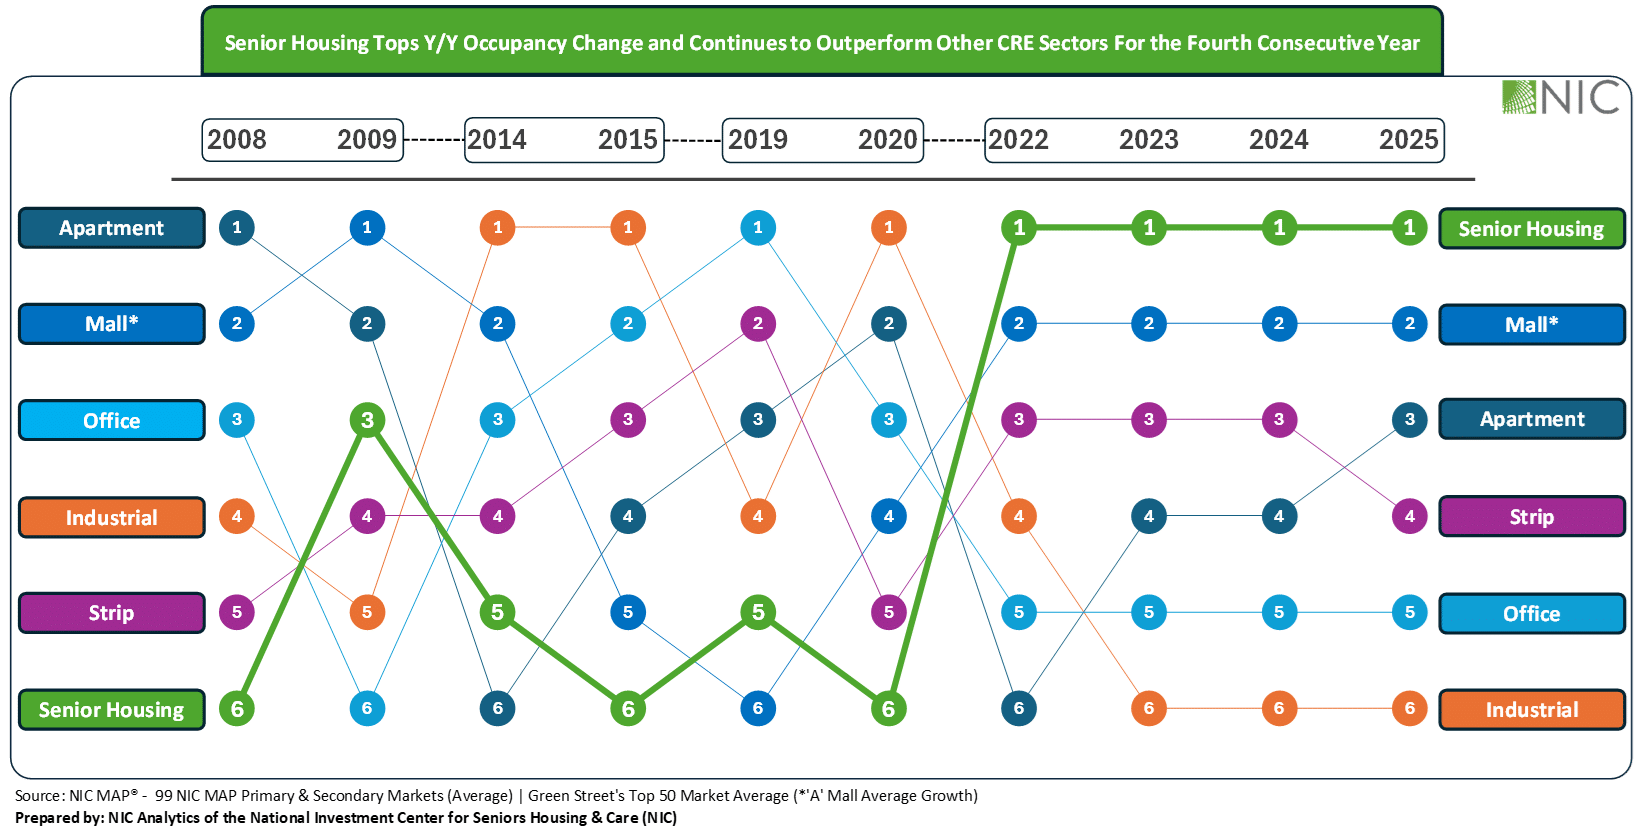
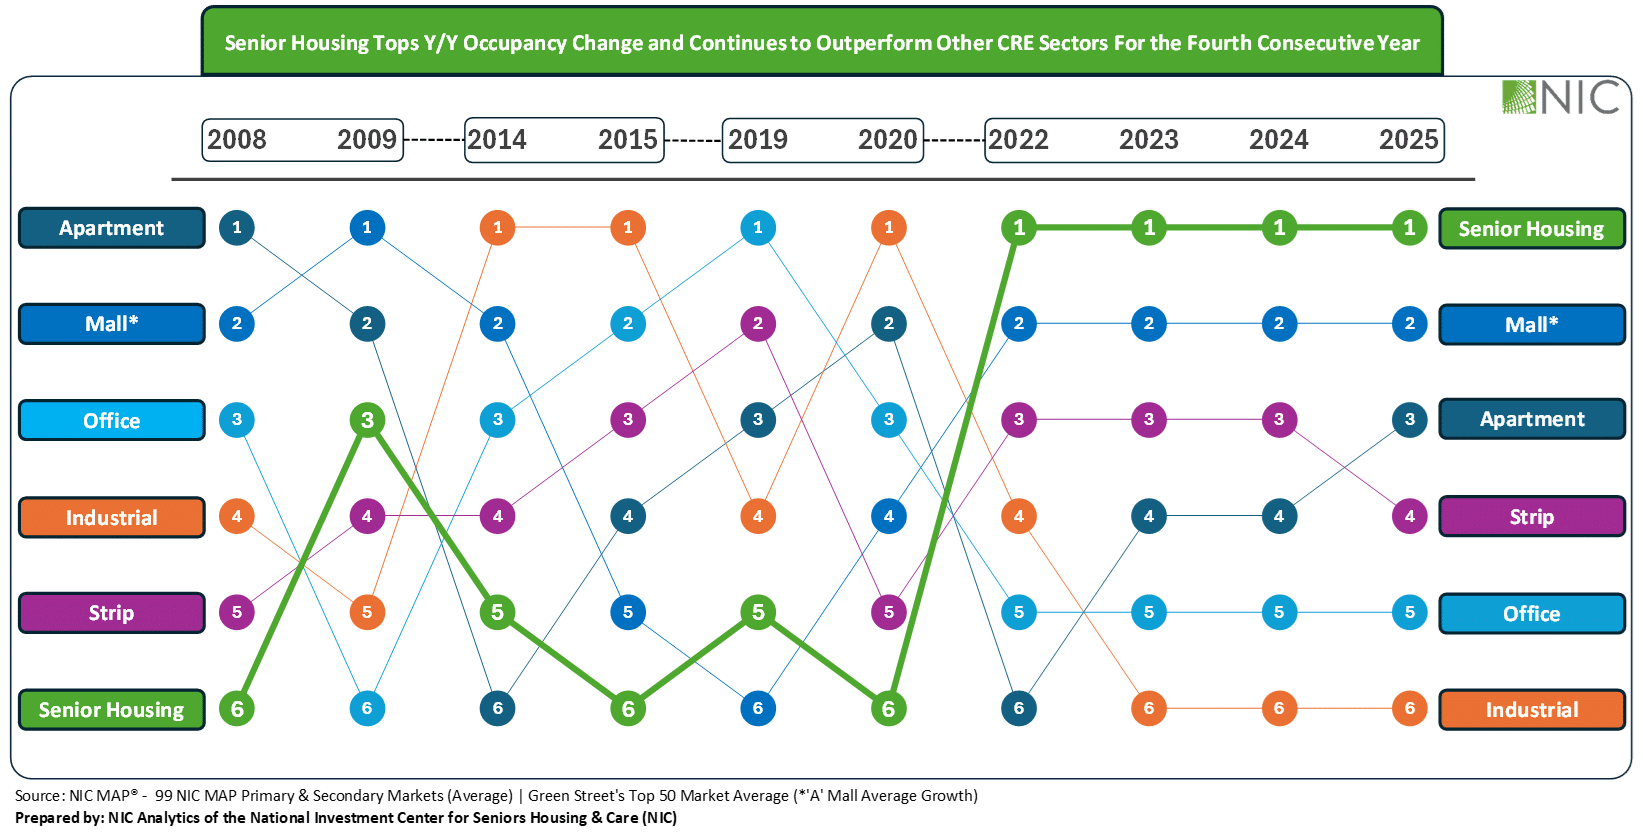
The evidence extends beyond the headline occupancy rate. For the fourth consecutive year, senior housing recorded the strongest year-over-year occupancy growth among all major commercial real estate sectors. At the same time, an increasing share of properties across the 31 Primary Markets are operating above 90% occupancy, while many others have already crossed the 85% threshold.
The next occupancy story will be written through occupancy distribution: understanding where occupancy is concentrated, and how many properties are approaching full capacity.
Four Years of Leadership Is Not a Coincidence
Commercial real estate has experienced dramatically different cycles over the past decade. Industrial benefited from e-commerce expansion, apartments experienced unprecedented demand during the housing shortage, office continues to adjust to structural workplace changes, and retail has undergone years of reinvention. Senior housing, meanwhile, has quietly accomplished something remarkable, it has led major commercial real estate sectors in year-over-year occupancy growth for four consecutive years.
Historically, that was rarely the case. In the years following the Global Financial Crisis, leadership rotated among apartments, industrial, malls, and office, depending on economic conditions. Senior housing experienced periods of strong performance but rarely maintained a sustained leadership position.
The Senior Housing Market Is Tightening
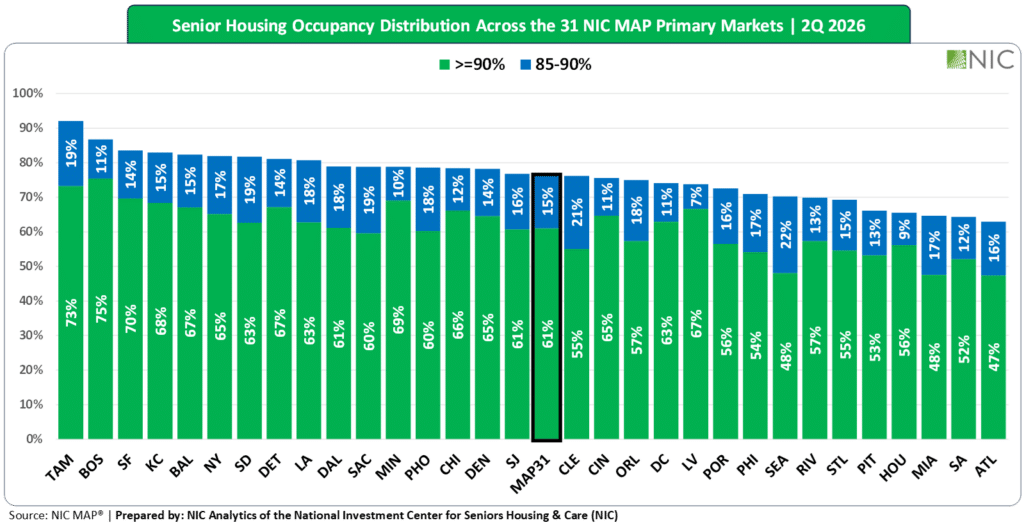
The occupancy distribution exhibit below tells us how the market is changing. Across the 31 Primary Markets, 61% of senior housing properties (6 out of 10) are now operating above 90% occupancy, while another 16% fall between 85% and 90%. In other words, more than three-quarters (77%) of all senior properties are already operating at occupancy levels above 85%.
Boston (75%), Tampa (73%), and San Francisco (70%) have the highest share of properties above 90% occupancy, but strong performance is by no means limited to a handful of markets. High occupancy levels are notable across markets with different demographic trends, economic conditions, migration patterns, and competitive dynamics.
While no single percentage defines a “full” market, properties operating at these levels generally have less flexibility to accommodate incremental demand. Available inventory becomes increasingly limited, prospective residents have fewer immediate options, and wait lists become more common.
For investors and developers, the implications are noteworthy. Markets with a growing concentration of highly occupied properties may signal limited remaining capacity, strengthening the case for new development where demographic demand, replacement costs, and expected investment returns support additional supply.
Every real estate sector reaches a point where growth begins to look different, and where occupancy becomes less about recovery or growth and more about the availability of space. Senior housing appears to be approaching that transition.
The latest occupancy distribution suggests that many markets are transitioning to a period of increasingly limited capacity. Although many projects are currently planned or under development, new properties require years to come online. As a result, the supply decisions being made today will shape market conditions, and the industry’s ability to meet growing demand, two or three years from now.
In conclusion, occupancy will always remain one of the industry’s most closely watched metrics, but it is no longer the only measure that matters. As operating costs continue to rise, particularly labor, insurance, and other expenses, the conversation is increasingly turning toward operating performance and margins. Strong occupancy creates opportunity, but it does not automatically translate into stronger financial performance.
In an upcoming article, NIC Research & Analytics will examine operating margin trends across the senior housing sector.
###
CCRC Performance 2Q 2026: Continued Demand for Memory Care
The following analysis examines broader occupancy trends, year-over-year changes in inventory, and same-store asking rent growth – by care segment – within 1,036 Continuing Care Retirement Communities (CCRCs) and 13,701 non-CCRCs in the 99 NIC MAP Primary and Secondary Markets.
2Q 2026 Market Fundamentals by Care Segment – CCRC (All) vs. Non-CCRC
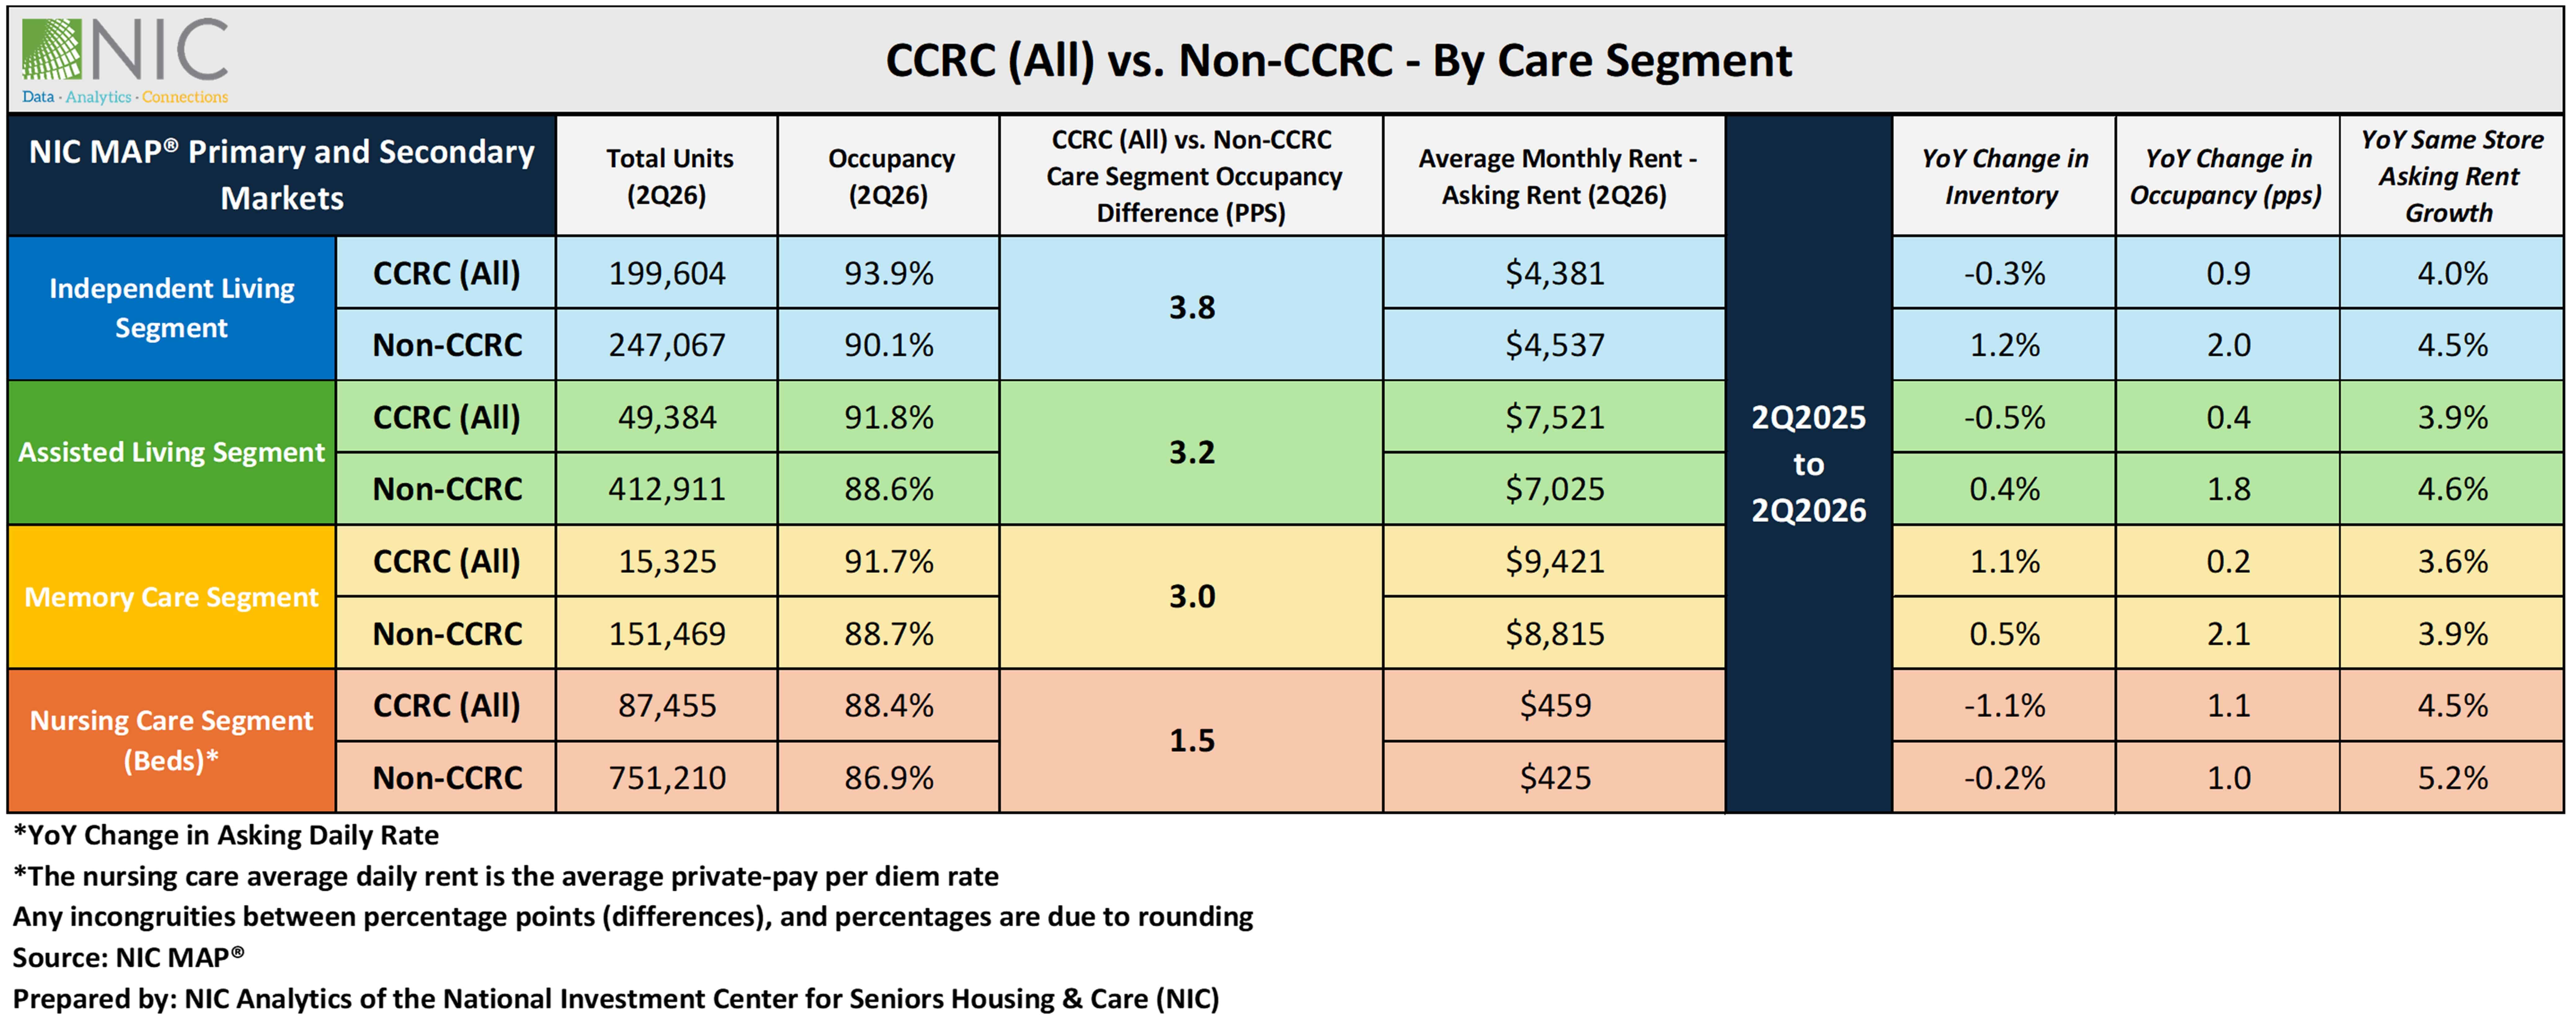
The exhibit below compares the market performance of CCRCs and non-CCRCs by care segment for the second quarter of 2026, highlighting year-over-year changes in occupancy, inventory, and asking rent growth.
Occupancy. Consistent with prior quarterly results, CCRCs continued to outpace non-CCRCs in occupancy rates across all care segments. The largest occupancy difference between CCRCs and their non-CCRC counterparts in the second quarter of 2026 was in the independent living segment (3.8pps), with the smallest gap in the nursing care segment (1.5pps). The independent living segment recorded the highest occupancy rate among both CCRCs (93.9%) and non-CCRCs (90.1%).
Non-CCRCs recorded higher year-over-year occupancy change in all care segments except for the nursing care segment, with memory care recording the highest change from the past year (2.1pps). While CCRCs overall have higher occupancy, the occupancy growth has been slower compared to non-CCRC communities.
Asking Rent. The average monthly asking rent (in dollars) for CCRCs continues to be higher than that of non-CCRCs across all care segments except for the independent living segment. Non-CCRCs experienced stronger year-over-year rent growth in all care segments with nursing care segment showing the highest growth (5.2%).
Note, these figures represent asking rates and do not reflect any discounts that may be applied. The nursing care average daily rent is the average private pay per diem rate.
Inventory. Compared to the level a year ago, nursing care inventory declined in both CCRCs (1.1%) and non-CCRCs (0.2%), the largest drops among the care segments. Among CCRCs, positive inventory growth was only seen in memory care segment (1.1%), while assisted living and independent living edged down slightly by 0.5% and 0.3 respectively.
For non-CCRCs, the strongest year-over-year inventory growth was recorded in independent living (1.2%) and memory care (0.5%) segments, while nursing care declined.
Negative inventory growth can occur when units or beds are temporarily or permanently taken offline or converted to another care segment, offsetting any newly added supply.
Memory Care Led CCRC Absorption in 2Q 2026
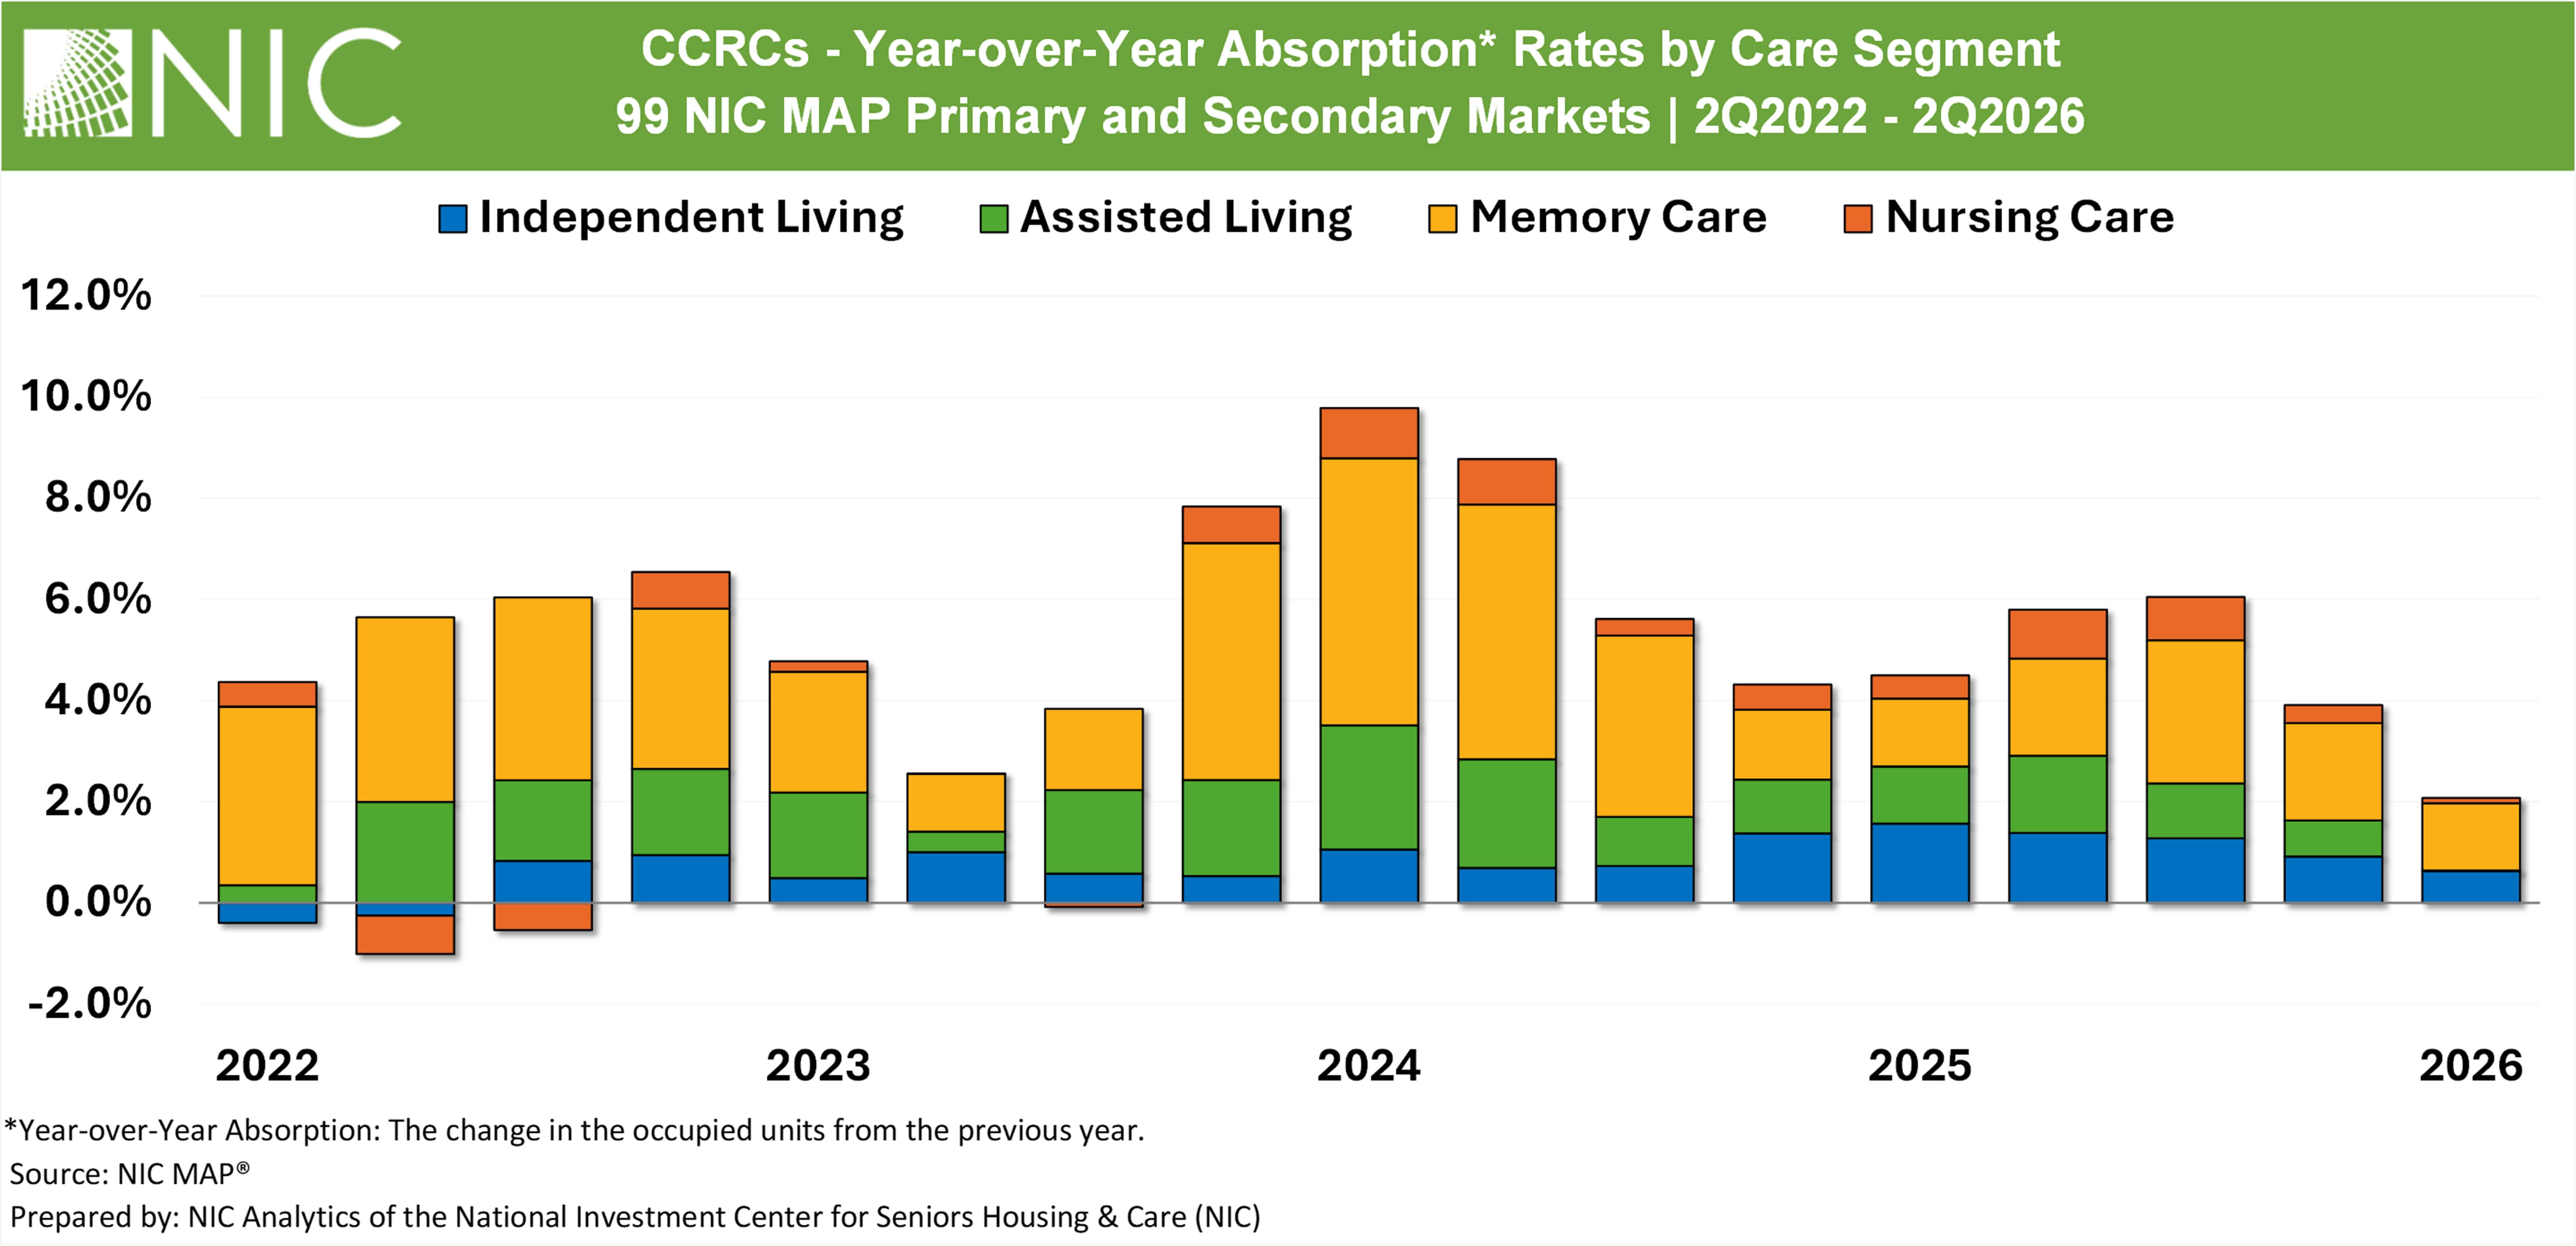
The exhibit below presents year-over-year absorption rates across all care segments within 1,036 Continuing Care Retirement Communities (CCRCs) in the 99 NIC MAP Primary and Secondary Markets.
Absorption. Memory care segment continued to post the strongest year-over-year absorption rate among CCRC care segments in the second quarter of 2026, as it has in most quarters since the second quarter of 2022. In the second quarter of 2026, the memory care segment led year-over-year absorption within CCRCs at 1.3%, followed by independent living (0.6%) and nursing care (0.1%), while assisted living was essentially flat (0.02%). Memory care has led absorption among CCRC care segments for four consecutive quarters. Compared with year-earlier levels, absorption moderated in three of the four segments; independent living from 1.6%, assisted living from 1.1%, and nursing care from 0.5% while memory care held near its second quarter of 2025 rate of 1.3%. Assisted living absorption was at its lowest level since the first quarter of 2022.
In conclusion, memory care within CCRCs continues to stand out as a strong performer, driven by leading absorption rates and steady inventory expansion. This ongoing trend highlights the critical role of memory care services, reinforcing their position as a durable and growing segment of the senior housing market.
Look for future articles from NIC to delve into the performance of CCRCs.
###
Another Strong Quarter for Senior Housing: Seven Straight Quarters of Outperformance
22 Senior Housing Properties Added to the NCREIF Property Index in 2Q
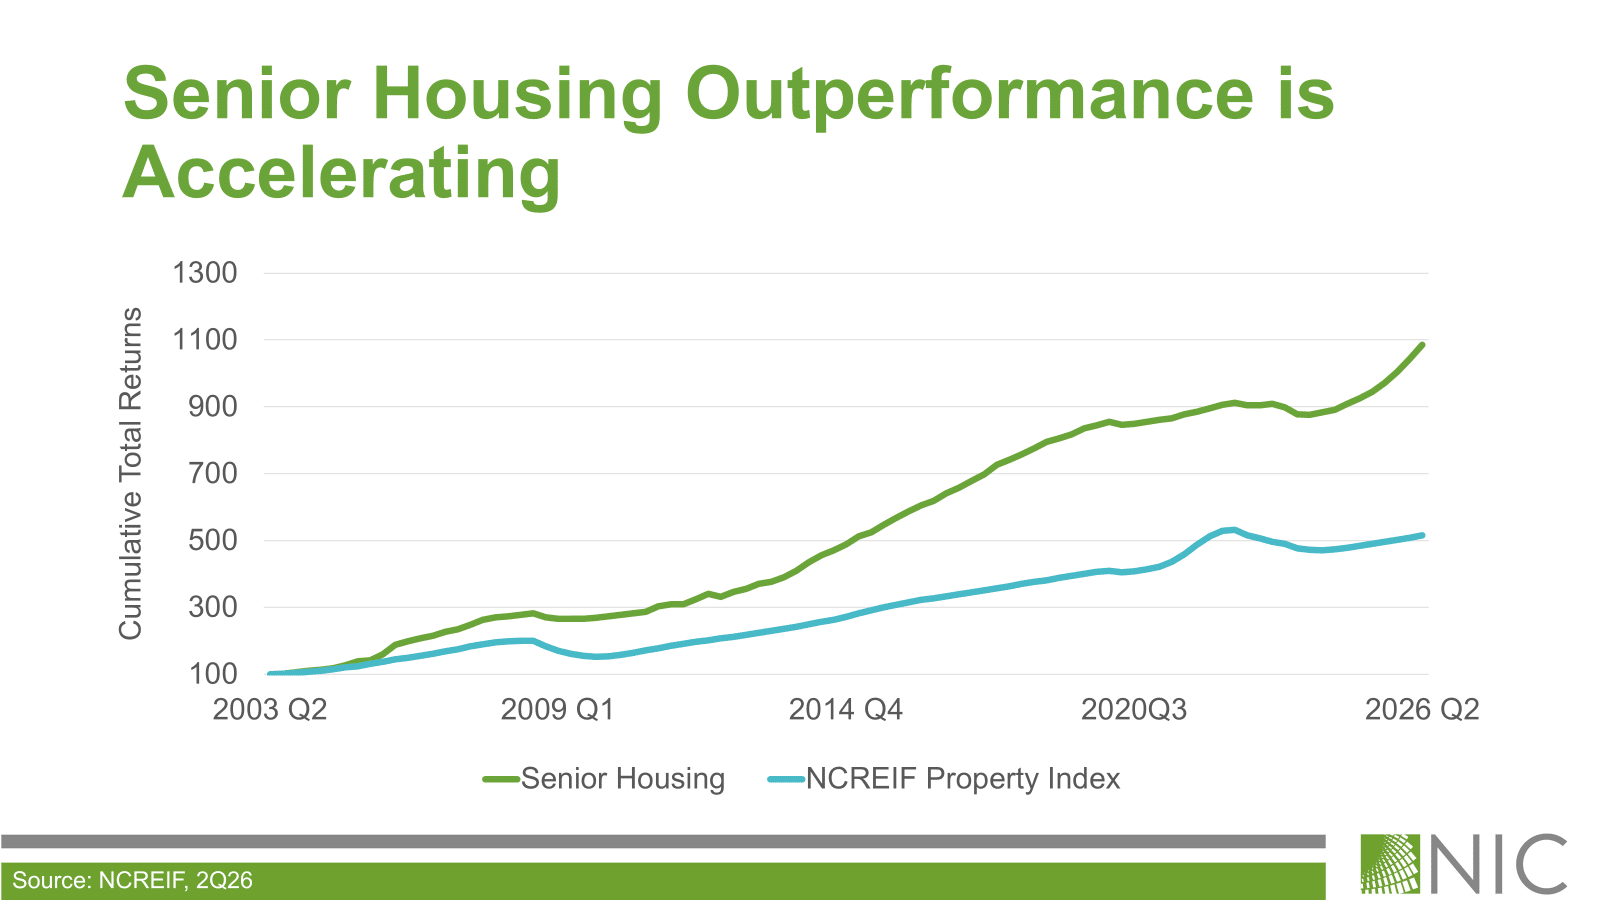
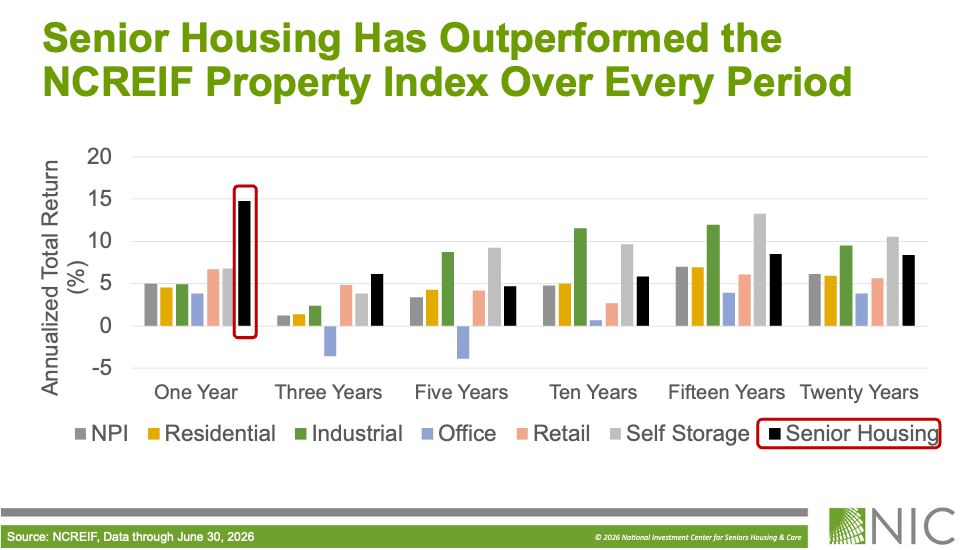
Senior housing investment performance in the second quarter of 2026 maintained the prior quarter’s momentum, posting a total return of 3.9% and bringing year-to-date returns to 8.0%. Overall, senior housing during the quarter outperformed the broader NCREIF Property Index’s (NPI) total return of 1.3% by 262 basis points, marking the seventh consecutive quarter of index outperformance.
Breaking out return contribution, senior housing capital appreciation in the second quarter was once again 2.5%. The capital appreciation return is the change in value net of any capital expenditures incurred during the quarter. Senior housing income return in the second quarter was also positive, once again yielding 1.4%. Both appreciation and income remained near their highest quarterly gains since 2017.
Over the one-year period, senior housing once again strongly outperformed all NCREIF Property Type Subindexes, posting the only double-digit total return at 14.8%, which was nearly ten percentage points above the NPI’s total return of 5.0% and well ahead of the next highest returns of 6.8% for self storage and 6.7% for retail properties. Over the longer run, senior housing has outperformed the NPI over the three-, five-, 10-, 15-, and 20-year periods.
These performance measures reflect the returns of 241 senior housing properties valued at $16.0 billion in the second quarter. Compared to the prior quarter, 22 senior housing properties were added to the index on a net basis, an increase of 24 assisted living properties and a decrease of two independent living properties. Overall, the number of senior housing properties tracked within the NPI has grown significantly from the 56 properties initially tracked in 2003, a reflection of increased institutional investment in the property type.
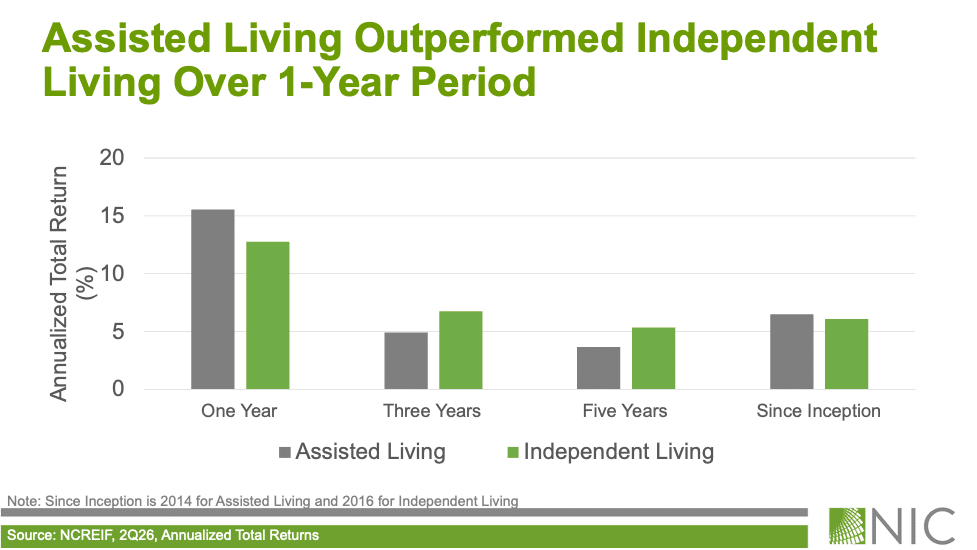
By senior housing property subtype in the second quarter, year-to-date, and one-year periods, assisted living outperformed independent living. Over the three- and five-year periods, however, independent living outperformed assisted living, likely driven by higher occupancy rates and lower labor costs. As of the second quarter of 2026, the gap in occupancy rates between independent living and assisted living narrowed to its smallest spread since 2014, and total returns for assisted living pulled ahead of independent living.
Over the long run, assisted living total returns have been comparable to independent living since their NCREIF inception periods of 2014 for assisted living and 2016 for independent living. Looking ahead, returns for the two property subtypes will likely continue to vary over certain time periods given that independent living is a choice-based product type while assisted living is driven by needs-based demand.
Turning to market fundamentals, as demand for senior housing has outpaced new supply, occupancy rates have climbed higher. Senior housing occupancy for the 31 Primary Markets tracked by NIC MAP gained 0.4 percentage points to 89.9% in the second quarter of 2026. This was the 20th consecutive quarter of increasing occupancy rates. At the current pace of development and demand, senior housing occupancy is on track to surpass 90% occupancy well before the end of the year, further tightening availability across many markets.
Total Return
Period
NCREIF Property Index (NPI)
Senior Housing
Assisted Living
Independent Living
2Q 2026
1.29
3.91
4.57
2.37
YTD
2.54
7.97
8.48
6.26
One Year
4.99
14.80
15.54
12.74
Three Years
1.22
6.10
4.92
6.76
Five Years
3.36
4.67
3.65
5.36
Ten Years
4.76
5.86
5.34
N/A
Fifteen Years
7.01
8.51
N/A
N/A
Twenty Years
6.12
8.39
N/A
N/A
Income
Period
NCREIF Property Index (NPI)
Senior Housing
Assisted Living
Independent Living
2Q 2026
1.17
1.40
1.48
1.30
YTD
2.33
2.85
3.03
2.64
One Year
4.71
5.69
6.02
5.31
Three Years
4.70
5.16
5.06
5.24
Five Years
4.45
4.49
4.21
4.82
Ten Years
4.49
4.80
4.62
N/A
Fifteen Years
4.82
5.37
N/A
N/A
Twenty Years
5.11
5.81
N/A
N/A
Appreciation
Period
NCREIF Property Index (NPI)
Senior Housing
Assisted Living
Independent Living
2Q 2026
0.12
2.51
3.09
1.08
YTD
0.20
5.05
5.37
3.57
One Year
0.27
8.73
9.12
7.15
Three Years
-3.36
0.91
-0.12
1.47
Five Years
-1.06
0.17
-0.54
0.53
Ten Years
0.26
1.03
0.70
N/A
Fifteen Years
2.12
3.03
N/A
N/A
Twenty Years
0.97
2.47
N/A
N/A
Source: NCREIF, Data through June 30, 2026
We use cookies on our website to give you the most relevant experience by remembering your preferences and repeat visits. NIC's privacy policy can be viewed here. By clicking “Accept”, you consent to the use of ALL the cookies.
This website uses cookies to improve your experience while you navigate through the website. Out of these cookies, the cookies that are categorized as necessary are stored on your browser as they are essential for the working of basic functionalities of the website. We also use third-party cookies that help us analyze and understand how you use this website. These cookies will be stored in your browser only with your consent. You also have the option to opt-out of these cookies. But opting out of some of these cookies may have an effect on your browsing experience.
Necessary cookies are absolutely essential for the website to function properly. This category only includes cookies that ensures basic functionalities and security features of the website. These cookies do not store any personal information.
Functional cookies help to perform certain functionalities like sharing the content of the website on social media platforms, collect feedbacks, and other third-party features.
Performance cookies are used to understand and analyze the key performance indexes of the website which helps in delivering a better user experience for the visitors.
Analytical cookies are used to understand how visitors interact with the website. These cookies help provide information on metrics the number of visitors, bounce rate, traffic source, etc.
Advertisement cookies are used to provide visitors with relevant ads and marketing campaigns. These cookies track visitors across websites and collect information to provide customized ads.